America’s Permanent Regime of Monetary Intervention vs The Leviticus 25 Plan

The Devil Neither Political Party Will Name

May 25, 2026 – Submitted by QTR’s Fringe Finance

Excerpt:
The widening wealth inequality gap is the political third rail nobody in power truly ever wants to touch.

Politicians will scream at each other all day over taxes, healthcare, immigration, tariffs, student loans, climate policy, or whatever outrage is currently driving engagement on cable news and social media. But the second the conversation turns toward monetary policy, toward the machinery of money creation itself, the room suddenly gets very quiet.

That’s because monetary policy has quietly become the single most powerful force reshaping wealth distribution in modern America. And unlike the endless partisan theater surrounding fiscal policy, monetary intervention oddly enjoys remarkable bipartisan support.

Republicans and Democrats may pretend to be existential enemies on television, but when it comes to flooding the financial system with dollars, both parties reliably fall into line. And that support is precisely why this topic is politically radioactive: once people understand how the system works, the illusion of two competing economic ideologies starts to collapse. Republicans want less spending, Democrats want higher taxes…but both parties want the Fed to keep printing dollars.
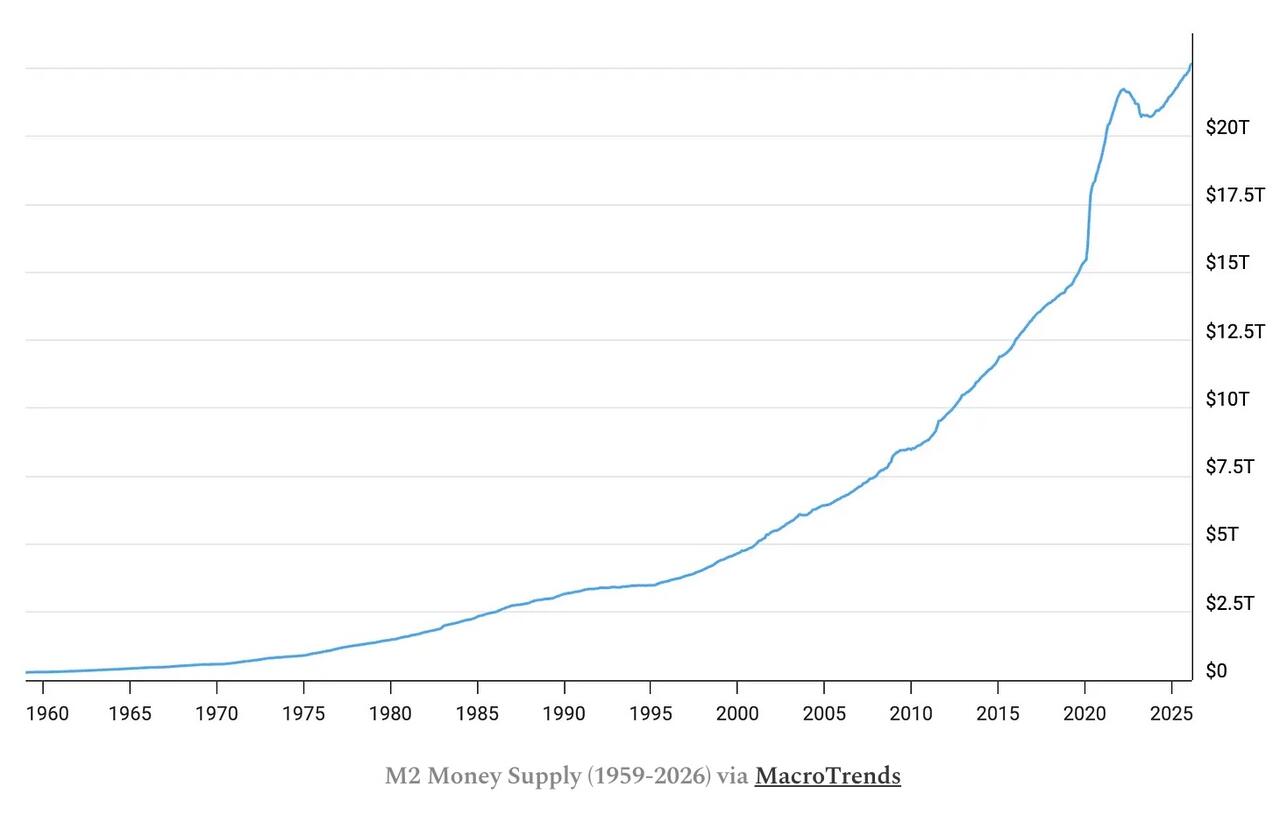
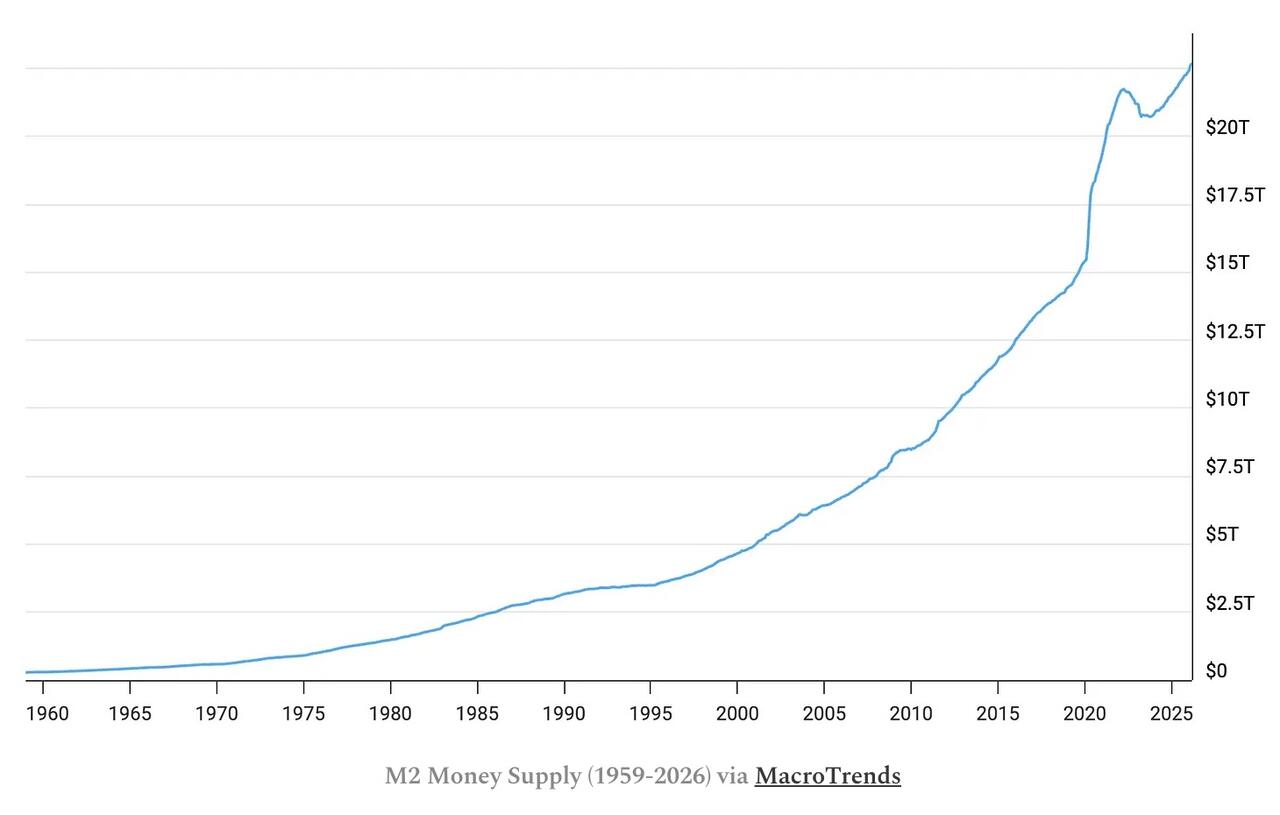
Since the early 2000s, and especially after 2008 and the COVID era, America has effectively entered a permanent regime of monetary intervention. Quantitative easing, near-zero interest rates, endless debt monetization, emergency lending facilities, and the mainstream acceptance of Modern Monetary Theory-adjacent thinking have fundamentally altered the structure of markets beyond recognition.

When Ben Bernanke first rolled out quantitative easing during the 2008 financial crisis, Americans were repeatedly assured it was a temporary emergency measure. Bernanke described the programs as targeted interventions designed to stabilize markets and support recovery, not permanently redefine the financial system.

QE1 was supposed to calm panic. Then came QE2. Then Operation Twist. Then QE3 became effectively open-ended, with the Fed purchasing tens of billions in bonds every month indefinitely. What began as a supposedly temporary crisis tool metastasized into a permanent feature of the modern economy. And every subsequent crisis only justified bigger interventions: larger balance sheets, lower rates, more liquidity, more market dependence on central bank support.

_______________________________

Federal Reserve monetary interventions (“Quantitative easing, near-zero interest rates, endless debt monetization, emergency lending facilities, and the mainstream acceptance of Modern Monetary Theory-adjacent thinking”) have indisputably favored Wall Street’s principal actors, and they have done so in grand fashion.

When insurance behemoth AIG collapsed during the 2008 financial crisis under the weight of their Financial Products division’s wild Credit Default Swap (CDS) gambling spree, the Federal Reserve Bank of New York and the U.S. Treasury Department stepped in to orchestrate their infamous $182 billion AIG bailout.

AIG had sold $440 billion of this ‘worthless CDS crap’ to various banks (like Goldman and the French multinational investment bank, Société Générale)… a large portion of which the “taxpayer ended up having to eat.”

AIG was taken over by the government in September 2008, and instead of the normal course of bankruptcy-arbitration, the government saw to it that “Goldman was paid 100 cents on the dollar on an additional $12.9 billion it was owed by AIG…”

Meanwhile, 8.7 million Americans lost their jobs (2008-2012), the national unemployment rate soared to 10%, and 6 million households lost their jobs.

The Leviticus 25 Plan is the most powerful Wall Street / Main Street counter-balancing economic acceleration machine in the world, and the only plan with the raw power to clean up America’s colossal fiscal dilemma.

The Leviticus 25 Plan is a dynamic economic initiative providing direct liquidity benefits for American families, while at the same time scaling back the role of government in managing and controlling the affairs of citizens.  It is a comprehensive plan with long-term economic and social benefits for citizens and government.

The inspiration for this plan is based upon Biblical principles set forth in the Book of Leviticus, principles tendering direct economic liberties to the people.

The Leviticus 25 Plan – An Economic Acceleration Plan for America

$95,000 per U.S. citizen – Leviticus 25 Plan 2027 (55727 downloads )
Fall 2008: State Street Corp – #5 Recipient of Fed’s “Secret Liquidity Lifelines”

State Street Corp, a Boston-based financial services holding company, is one of the oldest financial institutions in the U.S..  This multi-national corporation became the largest security services firm in the world in 2003 – even larger than JP Morgan and The Bank of New York Mellon.

State Street Corp was one of the top recipients of the Fed’s targeted liquidity ‘fire-hosing’ operations during 2008-2010.

Bloomberg  Nov 28, 2011Excerpts:

“Unlike banks that drew liquidity from the Federal Reserve in 2008 out of desperation, Boston-based State Street Corp. initially did so for profit. State Street, the third-largest U.S. custody bank, collected $75.6 million as a middleman for the Fed’s Asset-Backed Commercial Paper Money Market Mutual Fund Liquidity Facility, or AMLF. Under the program, it borrowed from the Fed to buy securities from money-market funds, helping them meet customer redemptions while being indemnified against losses on the securities. By October 2008, State Street had joined peers in tapping the Term Auction Facility and Commercial Paper Funding Facility, emergency-liquidity programs. On March 31, 2009, its total borrowings from the TAF and CPFF reached $18.5 billion, about the amount its excess liquidity fell that year.”                                                                                          

Peak amount of debt on 10/1/2008 :   $77.8 billion

________________________________________ 

The Federal Reserve’s massive balance sheet expansion during the Great Financial Crisis did nothing to solve America’s snowballing debt extravaganza, nothing to improve the long-term prospects for financial security for American families, nothing to stimulate long-term economic growth, and nothing to allay the ongoing erosion of the U.S. Dollar.

The Leviticus 25 Plan is a dynamic, ‘ground level’ solution with the raw power to eliminate vast tracts of public and private debt, and redirect trillions of dollars in debt service flows, much of it to the very banks that precipitated the 2008-2010 great financial crisis, back into the economy.

The Leviticus 25 Plan reduces ‘dependence on government’ for millions of Americans, re-establishes a market-based,economy, a citizen-centered health care system.

The Leviticus 25 Plan produces massive new tax revenue flows for federal, state, and local governmental entities. It produces $37.303 billion federal government surpluses during each of its first five years of activation, 2027-2031, and pays for itself entirely over the first 10-15 years.

It is time to create a bright new future for America.

The Leviticus 25 Plan is a dynamic economic initiative providing direct liquidity benefits for American families, while at the same time scaling back the role of government in managing and controlling the affairs of citizens.  It is a comprehensive plan with long-term economic and social benefits for citizens and government.

The inspiration for this plan is based upon Biblical principles set forth in the Book of Leviticus, principles tendering direct economic liberties to the people.

The Leviticus 25 Plan – An Economic Acceleration Plan for America

$95,000 per U.S. citizen – Leviticus 25 Plan 2025 (12113 downloads )

Fall 2008: Royal Bank of Scotland (RBS) – #4 Recipient of the Fed’s “Secret Liquidity Lifelines”

Bloomberg Nov 28, 2011:                                                                                                       “Royal Bank of Scotland Group Plc, whose 45.5 billion-pound ($74 billion) emergency capital injection from U.K. taxpayers was the world’s biggest announced bank bailout, also got more secret loans from the U.S. Federal Reserve than any other foreign bank. On Oct. 10, 2008, as the bank’s stock price plunged 21 percent in a single day, the Edinburgh-based RBS was borrowing $62.5 billion from the Fed through its U.S. broker-dealer, $11.5 billion through its New York branch, $10 billion through its RBS Citizens NA bank and $500 million through Citizens Bank of Pennsylvania. The Fed aid exceeded even the 36.6 billion pounds of emergency liquidity the Bank of England supplied in secret to RBS in October 2008. The BOE disclosed the aid package in November 2009, more than a year before the Fed aid was revealed.”

RBS’ secret liquidity line from the Fed served up a “peak amount of debt” totaling $84.5 billion on 10/10/2008.

RBS also happened to be one of a suspected dozen or so major banking interests involved in the big LIBOR ‘interest rate fixing” scandal – which bilked “U.S. states, counties, and local governments” to the tune of “at least $6 billion in fraudulent interest payments, above [and beyond the] $4 billion that state and local governments have already had to spend to unwind their positions exposed to rate manipulation,” according to Bloomberg (10 Oct 2012).

ZeroHedge 02/06/2013:  RBS Busted On Libor Manipulation: “its just amazing how libor fixing can make you that much money”

_________________________________

All of this leads, as a matter of course, to a very simple question: How can the Federal Reserve and U.S. Treasury justify the transfusion of massive liquidity streams into the veins of major banks like Morgan Stanley, Citigroup, Bank of America, and subsidiaries of major foreign banks like RBS (note: RBS blatantly manipulated LIBOR rates, to the detriment of states, counties and local governments)…

… While denying access to those same direct liquidity lines to American families – who have not broken any laws…?

It’s time to CORRECT these blatant imbalances.

The Leviticus 25 Plan is a dynamic economic initiative providing direct liquidity benefits for American families, while at the same time scaling back the role of government in managing and controlling the affairs of citizens.  It is a comprehensive plan with long-term economic and social benefits for citizens and government.

The inspiration for this plan is based upon Biblical principles set forth in the Book of Leviticus, principles tendering direct economic liberties to the people.

The Leviticus 25 Plan – An Economic Acceleration Plan for America

$95,000 per U.S. citizen – Leviticus 25 Plan 2027 (54914 downloads )

Fall 2008: Bank of America – #3 Recipient of Fed’s “Secret Liquidity Lifelines”

Bank of America – the story behind the story (Source:  Bailout Nation)

June 2005:  Bank of America takes a 9 percent stake in China Construction Bank for #3 billion; China’s market tops out in 2007 and then plummets 72 percent.

January 2006:  Bank of America acquires MBNA for $35 billion.  The world’s largest issuer of credit cards [MBNA] is taken over right before the world’s largest credit crunch occurs and (whoops) just before the worst postwar recession begins.

August 2007:  Bank of America invests $2 billion in Countrywide Financial, the nation’s biggest mortgage lender and loan servicer.  It is a jumbo loser, dropping 57 percent in a few month’s time

January 2008:  Bank of America doubles down and announces a $4.1 billion acquisition of Countrywide.  The timing is flawless, and the purchase is announced as the worst housing collapse in modern history is accelerating.

September 2008:  Bank of America pays $50 billion for Merrill Lynch, including Merrill’s portfolio of toxic assets (along with some previously unannounced trading desk errors).

……………………………………

Note – following the above cited BofA follies, the Treasury Department and the Federal Reserve stepped up to the plate and kindly dished out billions of dollars (at U.S. citizen taxpayer expense) to Bank of America to keep the big dog afloat.

To recap (Source: Bloomberg Nov 28, 2011 ):                                                                Morgan Stanley was the #1 recipient of Fed secret loans at $107 billion (peak loan amount – 9/29/2008).                                                                                                

Citigroup was the #2 recipient of the Fed’s secret lifelines $99.5 billion (peak loan amount – 1/20/2009).                                                                                                  

Bank of America was the #3 recipient with $91.4 billion (peak loan amount –  2/26/2009).

Bloomberg Nov 28, 2011:  “Bank of America Corp., which got two rounds of U.S. Treasury Department capital injections totaling $45 billion to stay afloat during the credit crisis, borrowed twice that amount in secret from the Federal Reserve. On Feb. 26, 2009, the Charlotte, North Carolina-based bank held $78 billion of loans from the Fed’s Term Auction Facility, $8.65 billion from the Primary Dealer Credit Facility, $4.75 billion from the Term Securities Lending Facility. The financing helped bolster the largest U.S. bank by assets as investors worried its 2008 acquisitions of Merrill Lynch & Co. and Countrywide Financial Corp. might lead to nationalization.”

………………………………………….

A final question: Is there anyone who still believes that it is OK for major Wall Street banking and financial services institutions to receive massive liquidity injections (at taxpayer expense) when their financial viability evaporates … due to their own failed risk management strategies and reckless, yield-driven investment decision-making….

But it is not OK for U.S. citizens to be accorded the same access to direct liquidity extensions?

It is time now to level the playing field… and activate a Federal Reserve / U.S. Treasury pipeline via a U.S. Citizens Credit Facility.

The Leviticus 25 Plan will generate $37.303 billion federal budget surpluses (2027-2031) and pay for itself entirely over the succeeding 10-15 years.

The Leviticus 25 Plan – An Economic Acceleration Plan for America

$95,000 per U.S. citizenLeviticus 25 Plan 2027 (54362 downloads )

Fall 2008: Citigroup – #2 Recipient of Fed’s “Secret Liquidity Lifelines”

Citigroup – Following the repeal of the Glass-Steagall Act in 1998, Citigroup dove headlong into the derivatives market.  “By 2007 Citi was the largest issuer of CDOs [Credit Default Obligations] … $49 billion worth when the world’s total production was $442 billion.” (Source: Bailout Nation)

Citi later took advantage Structured Investment Vehicles (SIVs) to move high-risk investments off their balance sheets – into “Enron-like side pockets.”

When the housing market began staggering badly in 2007 under the weight of increasing loan delinquencies and foreclosures, “Citigroup’s SIVs were festooned with $87 billion of toxic assets, mortgage-related CDOs, and other long-term paper…. ”

Short-term financing dried up, and the SIVs worked their way back “in-house.”  And “by December 2007, Citi assumed $58 billion of debt to ‘rescue’ $49 billion in Assets.” (Bailout Nation)

The Federal Reserve then cranked open the “Secret Loan” fire hose to flood Citi (and scores of others) with massive liquidity injections (or, in the common parlance, ‘free money’).

Citigroup – #2 recipient of Fed Secret Loans (2008-10)                                                 Bloomberg – Nov 28, 2011

“Citigroup Inc., the third-largest U.S. bank by assets, received a $45 billion capital injection in 2008 from the U.S. Treasury. The New York-based lender got a bigger bailout from the Federal Reserve: $99.5 billion of emergency loans, about the cost of paying, clothing, housing, arming and transporting the U.S. Army for fiscal 2011. On Jan. 20, 2009, as the bank’s shares fell to $2.80, down almost 90 percent in a year, its Fed loans included $34.1 billion from the Term Securities Lending Facility, $25.1 billion from the Commercial Paper Funding Facility, $25 billion from the Term Auction Facility, $14 billion from the Primary Dealer Credit Facility and $1 billion from single-tranche open market operations.”

Citigroup peak loan amount (1/20/2009): $99.5 billion      

_______________________

U.S. citizens deserve nothing less than the same direct access to credit extensions that was provided to Morgan Stanley, Citi, and the dozens of other financial enterprises whose high risk investment profiles led to financial calamity and rescue action by the Federal Reserve.

It is time now for the Fed to extend credit to American families via a “U.S. Citizens Credit Facility.”

The Leviticus 25 Plan is a dynamic economic initiative providing direct liquidity benefits for American families, while at the same time scaling back the role of government in managing and controlling the affairs of citizens.  It is a comprehensive plan with long-term economic and social benefits for citizens and government.

The inspiration for this plan is based upon Biblical principles set forth in the Book of Leviticus, principles tendering direct economic liberties to the people.

The Leviticus 25 Plan – An Economic Acceleration Plan for America

$95,000 per U.S. citizenLeviticus 25 Plan 2027 (54359 downloads )

Fall 2008: Morgan Stanley – #1 recipient of Fed’s ‘secret liquidity lifelines’

A look back…

As the banking crisis intensified in the Fall of 2008, with major banking institutions assuming, or on the verge of assuming, the classical ‘snorkel’ position (aka ‘underwater’ status), the Federal Reserve ran quickly to the rescue with secret liquidity lifelines” (Bloomberg 8-22-11).

The Fed substantially eased some important collateral rules for banks, “meaning that banks that could once borrow only against sound collateral, like Treasury bills or AAA-rated corporate bonds, could now borrow against pretty much anything – including some of the mortgage-backed sewage that got us into this mess in the first place….  ‘All of a sudden, banks were allowed to post absolute [expletive deleted] to the Fed’s balance sheet,’ [according to] the manager of the prominent hedge fund.” (Source: Bailout Hustle, Matt Taibbi).

The Federal Reserve ‘created’ various “facilities” to fire-hose liquidity out to major domestic and foreign banks, insurers, and brokerage firms, to include: Primary Dealers’ Credit Facility, Term Securities Lending Facility, Temporary Liquidity Guarantee Program, Commercial Paper Funding,Term Auction Facility, Public Private Investment Program

And, here we go – from the top (Bloomberg  Nov 28, 2011) :

Morgan Stanley, facing a crisis of confidence after the fall of Lehman Brothers Holdings Inc., got a $9 billion injection from Japanese bank Mitsubishi UFJ Financial Group Inc. and agreed to take a $10 billion bailout from the U.S. Treasury to shore up capital. As hedge-fund customers pulled funds out of the New York-based firm, it plugged the hole with $107.3 billion of secret loans from the Federal Reserve’s Primary Dealer Credit Facility and Term Securities Lending Facility, set up earlier in the year to supply brokerage firms with emergency financing.”

Peak amount of Debt on 9/29/2008:  $107B
………………………………………………………………

The Leviticus 25 Plan does not seek to ‘interrupt’ or reverse any of the special relationships that have developed in the Fed’s financial sphere.  It only seeks to level the playing field by providing U.S. citizens the same access to direct liquidity flows that the big banks enjoyed ‘in their time of need.’

The Leviticus 25 Plan proposes one additional upgrade to the Fed’s liquidity lines: A U.S. Citizens Credit Facility.

The Leviticus 25 Plan – An Economic Acceleration Plan for America

$95,000 per U.S. citizenLeviticus 25 Plan 2027 (54252 downloads )

The Leviticus 25 Plan vs the ‘Permanent Regime of Monetary Intervention’

The Leviticus 25 Plan puts hard-working, tax-paying U.S. citizens front and center in a dynamic reset plan for the U.S. economy.

………………………………………….

QTR’s Fringe Finance, May 25, 2026 – Excerpt:

Republicans want less spending, Democrats want higher taxes…but both parties want the Fed to keep printing dollars.

Since the early 2000s, and especially after 2008 and the COVID era, America has effectively entered a permanent regime of monetary intervention. Quantitative easing, near-zero interest rates, endless debt monetization, emergency lending facilities, and the mainstream acceptance of Modern Monetary Theory-adjacent thinking have fundamentally altered the structure of markets beyond recognition.

When Ben Bernanke first rolled out quantitative easing during the 2008 financial crisis, Americans were repeatedly assured it was a temporary emergency measure. Bernanke described the programs as targeted interventions designed to stabilize markets and support recovery, not permanently redefine the financial system.

QE1 was supposed to calm panic. Then came QE2. Then Operation Twist. Then QE3 became effectively open-ended, with the Fed purchasing tens of billions in bonds every month indefinitely. What began as a supposedly temporary crisis tool metastasized into a permanent feature of the modern economy. And every subsequent crisis only justified bigger interventions: larger balance sheets, lower rates, more liquidity, more market dependence on central bank support.

__________________________________

The Leviticus 25 Plan will achieve extraordinary gains within the U.S. economy that all of Fed’s “Quantitative easing, near-zero interest rates, endless debt monetization, emergency lending facilities” over the past two decades have failed entirely to produce.

The Leviticus 25 Plan will retarget Fed / U.S. Treasury liquidity extensions through a Citizens Credit Facility directly to qualifying U.S. citizens who wish to participate – to generate four unprecedented gains:

  1. The Plan will generate average annual budget surpluses of $37.303 billion vs current CBO-projected average annual deficits of $1.982 trillion – over each of the first five years of activation (2027-2031);
  2. Massive debt elimination and restored financial security for millions of hard-working, tax-paying American families;
  3. Robust, long-term economic growth – not financed by debt;
  4. Fundamental gains in U.S. and global credit market stability, U.S. Dollar strength and integrity.

The Leviticus 25 Plan is a dynamic economic initiative providing direct liquidity benefits for American families, while at the same time scaling back the role of government in managing and controlling the affairs of citizens.  It is a comprehensive plan with long-term economic and social benefits for citizens and government.

The inspiration for this plan is based upon Biblical principles set forth in the Book of Leviticus, principles tendering direct economic liberties to the people.

The Leviticus 25 Plan – An Economic Acceleration Plan for America

$95,000 per U.S. citizen – Leviticus 25 Plan 2027 (53959 downloads )

Record Low Consumer Sentiment: “Americans haven’t been this gloomy in 70 years.” – WSJ

WSJ: The Stock Market Has Never Been So Good When People Have Felt So Bad

Excerpt:

Americans are in a decidedly bad mood. The stock market is decidedly not.

This isn’t how it usually works. Instead, high stock prices have historically been associated with happy consumers, and vice versa. Here’s a look at what’s going on.

Just How Bad is Sentiment?

American attitudes just hit a milestone of sorts. On Friday, the University of Michigan reported that its index of consumer sentiment fell to the lowest level ever recorded in 70-odd years of surveys.

Sentiment was already low at the start of this year, but it fell sharply after the Iran war began at the end of February and sent gas prices sharply higher.

Until this year, the previous lowest level was in June 2022, when inflation was running at the highest level in decades. Friday’s sentiment reading was 10% below even that number. 

“Prices remain extremely high, labor markets have unambiguously weakened in the last four years, and now we’re in the middle of a war,” said Joanne Hsu, director of consumer surveys for the University of Michigan. “I don’t think the fact that we’re lower than June 2022 should come as a surprise to anyone.”

Full article: https://www.wsj.com/economy/consumers/stock-market-consumer-sentiment-af088e87

_________________________________

The vast majority of U.S. households fall beneath 90th percentile of the income and wealth distribution. This massive demographic, the “bottom 90%, captures a wide spectrum of Americans, from working-class individuals to middle-class professionals.

America’s record low consumer sentiment is primarily focused within this wide-ranging demographic, while at the same time, Wall Street has been feasting on record gains.

Democrat socialists in America are pushing hard for massive wealth redistribution, setting up ever greater levels of gloom and the eventual destruction of the U.S. economic system.

Main Street America Republicans have a plan that will eliminate massive amounts of debt, reignite economic growth and restore financial security for the millions of families counted among America’s “bottom 90%.”

This plan levels out the America’s economic playing field by granting hard-working, tax-paying U.S. citizens the same direct access to liquidity extensions that were so generously provided by the Federal Reserve (2008-2010 and 2021-2022) to the likes of: Morgan Stanley, Bank of America, Citigroup, JP Morgan, Goldman Sachs, State Street, AIG, Merrill Lynch, Wells Fargo… Barclays, UBS AG, Deutsche Bank, HSBC, Royal Bank of Scotland, BNP Paribas, Dexia, and numerous others.

The Leviticus 25 Plan – An Economic Acceleration Plan for America

$95,000 per U.S. citizen – Leviticus 25 Plan 2027 (53622 downloads )

Hubbard: “Bailouts Shouldn’t Be Only for Banks.”

Glenn Hubbard, dean of the Columbia Business School and former chairman of the Council of Economic Advisers during the George W. Bush presidency,. recently urged that financial crisis interventions should not be limited to banks.

………………………………………………

*Bailouts Shouldn’t Be Only for Banks – WSJ

Wall Street Journal, 9-14-18 – Excerpts:

“To be sure, recapitalizing financial institutions was an important element of the policy response. The depletion of capital buffers before the crisis reduced loan supply and exacerbated fire sales of distressed assets once the market collapsed. Cash infusions by the Treasury under the Troubled Asset Relief Program, in concert with the Fed’s bold lender-of-last-resort interventions, blunted the impact of the crisis.

That said, the perceived lack of attention to “Main Street” fed public suspicion of the bailouts. The government appeared to be more interested in addressing the decline in bank capital than the decline in home values. Millions of homeowners who were current in their mortgage payments were unable to refinance at lower interest rates because they were underwater. Yet many of these mortgages were already guaranteed by Fannie Mae and Freddie Mac , meaning taxpayers held the credit risk. Banks and investors holding the mortgages would never receive less than par.

The government should have directed a mass refinancing of mortgages for primary homes in which the borrower was current in payments. This would have led to an increase in disposable income and in home prices totaling more than $100 billion, according to a proposal Christopher Mayer and I offered at the time. The Treasury instead offered a tepid version of this with the Home Affordable Modification Program and the Home Affordable Refinance Program. These initiatives lacked the boldness of the bank bailouts, and Americans noticed…”

Hubbard concluded, “Ten years on, the U.S. still lacks a detailed plan for postcrisis intervention…”

____________________________

What America really needs, to restore financial health to working families and ‘power up’ economic vitality throughout Main Street America – is a detailed plan for ‘pre-crisis’ intervention.

America needs a comprehensive economic plan that will insulate Main Street America’s hard-working, tax-paying U.S. citizens from the next financial crisis, shrink government’s massive footprint in controlling the lives of free Americans, and generate massive new tax revenue flows with a powerful, sustainable reduction in government deficits.

America’s new economic plan is currently loaded up and ready to launch…

The Leviticus 25 Plan – An Economic Acceleration Plan for America

$95,000 per U.S. citizen – Leviticus 25 Plan 2027 (52432 downloads )

America’s Financial Woes – A Perfect Opening for ‘Quantitative Re-targeting” (QR)…

Headlines…

US Businesses Are Going Bankrupt At An Absolutely Blistering Pace

Our society is changing at a pace that is difficult to comprehend…  DEC 5, 2025

……….

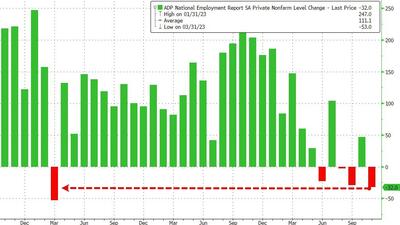
Small Business Job Losses Soar In November; ADP

That is the biggest monthly job loss since March 2023DEC 3, 2023

……………

Food Banks All Over The US Are Being Overwhelmed By A Tsunami Of Hungry People …experiencing a dramatic spike in demand “long before the shutdown ever happened”…  NOV 7, 2025

……………

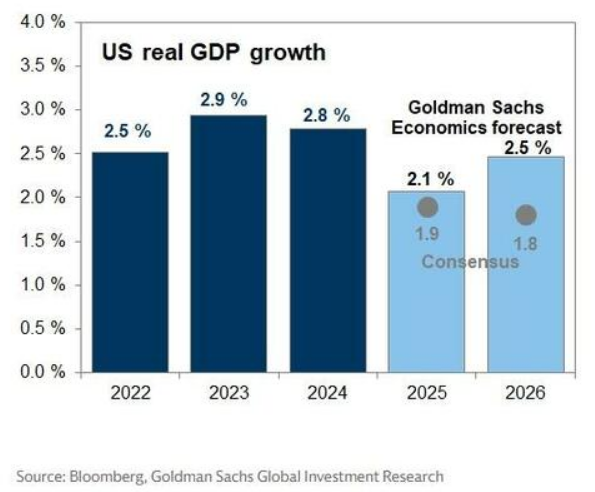
Stagnation …

Also note: lower GDP growth means lower Treasury receipts, lower payroll tax revenues and more stress on the Medicare and Social Security Trust Funds…

………………..

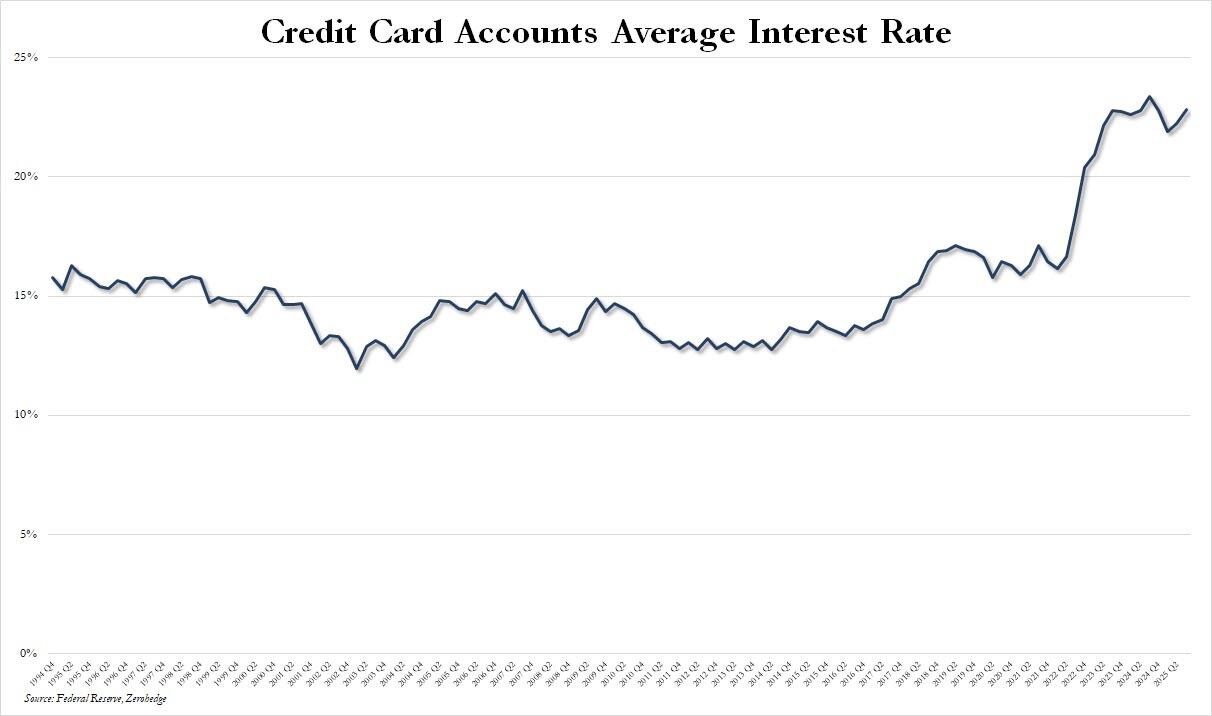
Federal Reserve’s latest consumer credit report (G.19):

Finally… banks continue to bleed US consumers dry: at the start of 2025 the average rate on credit card accounts was 22.80%… and on Sept 30 the number was higher at 22.83%, just barely below the all time high of 23.37% set one year ago.

_____________________________________

The Leviticus 25 Plan solution

Quantitative Easing (QE) is a Fed monetary tool used to restore liquidity in a troubled banking system, as when banks fall below their capital requirements through practices like loading up balance sheets with sewage-grade subprime debt delivered up the line from the mortgage broker casino system, aided and abetted by fake AAA credit ratings on their bundled security packages, topped off with gross incompetence / ignorance in properly assessing counter-party risk in their hedging strategies.

The Great Financial crisis (2007–2009) which followed “created the largest economic upheaval in the United States since the Great Depression of the 1930s… At eighteen months, from December 2007 to June 2009, it exceeded the sixteen-month recessions of 1973–1975 and 1981–1982; the average period from peak to trough of post–World War II recessions was 11.1 months… both GDP and number of jobs declined by about 6 percent and median family incomes declined by about 8 percent. The Great Recession was particularly worthy of its name because of the protracted slump in employment that followed even after the recession was officially over, as assessed on the basis of the dating procedure of the National Bureau of Economic Research.1

By some estimates, over 30 million working Americans lost their jobs; over 3.8 million families lost their homes.

QE has done nothing to reduce public and private debt, or restore financial security for millions of American families or strengthen our country’s economic system.

It is now time for a major reset involving a Fed-Treasury Quantitative Re-targeting (QR) facility – with direct liquidity flows to all of America’s hard-working, tax-paying U.S. citizens who qualify and wish to participate.

The Leviticus 25 Plan is a dynamic economic initiative providing direct liquidity benefits for American families, while at the same time scaling back the role of government in managing and controlling the affairs of citizens.  It is a comprehensive plan with long-term economic and social benefits for citizens and government.

The inspiration for this plan is based upon Biblical principles set forth in the Book of Leviticus, principles tendering direct economic liberties to the people.

The Leviticus 25 Plan – An Economic Acceleration Plan for America

$95,000 per U.S. citizen – Leviticus 25 Plan 2027 (52102 downloads )