Fed IORB Payments Subsidize Wall Street’s Largest Banks, Major Foreign Banks

U.S. Senate Committee on Homeland Security & Governmental Affairs – December 2025

Excerpts:
Executive Summary

On July 15th, 2025, Chairman Rand Paul of the U.S. Senate Committee on Homeland Security and Governmental Affairs (HSGAC) launched an investigation on the Federal Reserve’s use of Interest on Reserve Balances (IORB). After months of correspondence, the Federal Reserve Board of Governors produced over 40,000 pages of documents detailing IORB payments for every two-week period from July 2013 through July 2025.

July 2013 through July 2025. This report outlines the following key findings from the contents of the data:

  1. IORB payments equal 10 percent of the Federal Deficit:
    a. The magnitude of IORB payments equaled 10.3 percent ($187 billion) of the
    FY24 Federal deficit and 8.8 percent ($149 billion) of the FY23 deficit.
  2. The Federal Reserve has used IORB payments to subsidize Wall Street’s largest banks:
    a. IORB payments account for 12 percent of all profits for the 5 largest American
    banks from 2013-2024.
    b. In 2024, IORB payments accounted for 16 percent of U.S. banking sector’s
    net interest income.
    c. The top 20 banks account for over half ($305 billion) of total payments with
    the remaining 4,500 banks accounting for the remaining half ($302 billion).
  3. IORB payments are also subsidizing foreign banks:
    a. 11 of the top 20 recipients of IORB payments are foreign banks.
    b. From July 2013 – July 2025, $235 billion has been paid to foreign banks by
    the Fed through IORB payments (see figure 9).
    c. $10 billion of these payments were made to Chinese banks such as Bank of
    China, China Construction Bank, Industrial and Commercial Bank of China,
    and Bank of Communication…..

…………

IORB Rates Rise

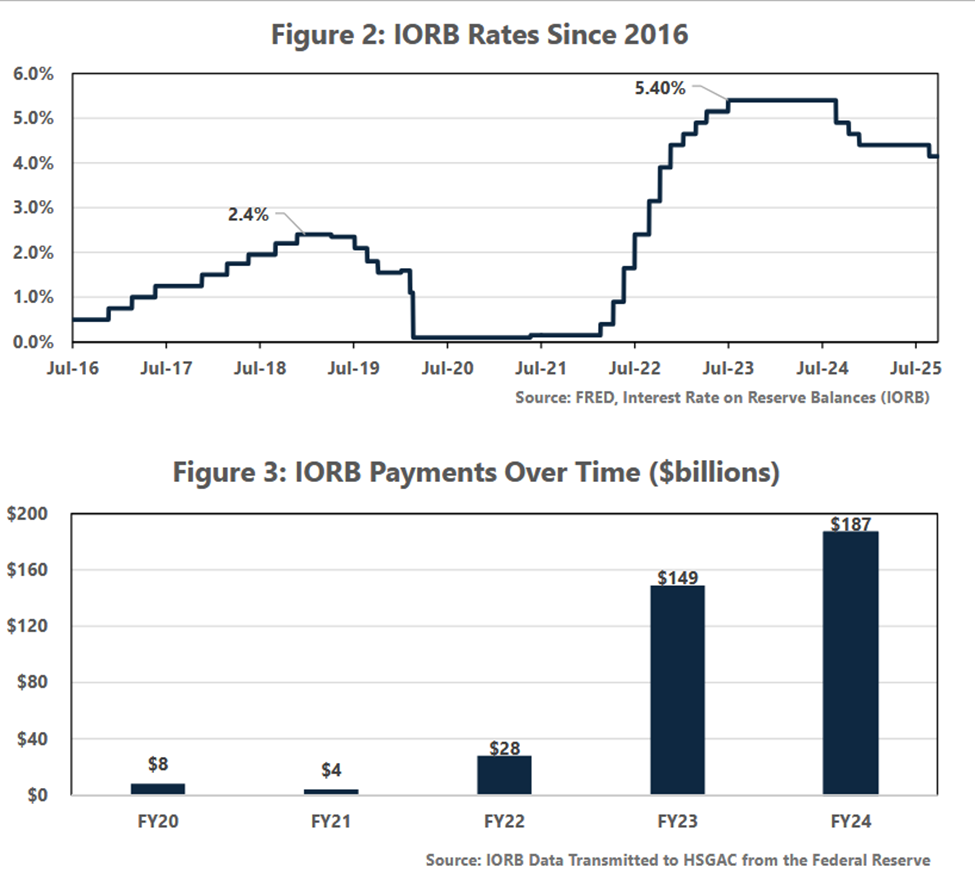
Prior to 2021, IORB rates peaked at 2.4 percent, however in the inflationary period after the COVID stimulus in 2021, the Fed began to raise rates in an attempt to rein in inflation. The Fed raised IORB rates to a high of 5.4 percent in July 2023 (see figure 2).

The Fed’s increased IORB rates incentivized eligible domestic and foreign banks to place reserves at the Fed instead of lending out these funds, buying treasury bills, or other financial activities effectively setting a floor on interest rates. IORB payments from the fed ballooned from an average of $17 billion prior to the pandemic to over $100 billion in each of the last two fiscal years (See figure 3).
IORB Payments as Corporate Welfare

Introduction – IORB payments, as currently structured, take the Fed’s operating profits that could be used to pay down the deficit and pay these funds out to the world’s largest banks. Since 2013, the Fed has paid $607 billion in identified payments to both foreign and domestic financial institutions to keep their reserves idle and interest rates artificially high. This costly means of conducting monetary policy has prevented the Fed from remitting profits to Treasury to pay down the Federal deficit and instead directed these funds into Wall Street’s profit margins.

Characteristics of IORB Payment Recipients

Analysis of these payments shows that large banks are the primary beneficiary of this reallocation of taxpayer funds. The allocation of IORB payments is disproportionately skewed to large financial institutions. The top 20 bank recipients (see Figure 6) received approximately the same amount of IORB payments from 2020-2025 ($305 billion) as the next 4,500 banks received ($302 billion).

IORB Payments as a Driver of Bank Profits

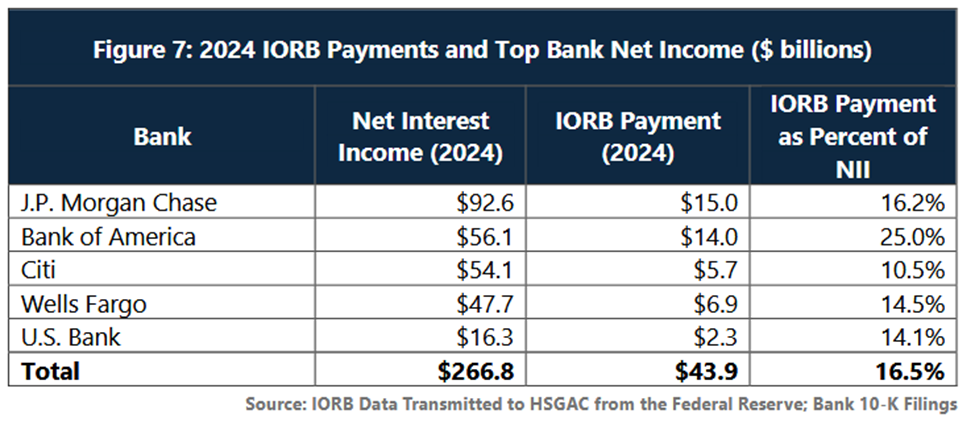
The five largest banks in the U.S. by consolidated assets: JP Morgan Chase, Bank of America, Citibank, Wells Fargo, and U.S. Bank received $136 billion in IORB payments from 2013 to 2024, with 2024 payments alone amounting to $43.9 billion. In 2024, taxpayer-financed IORB payments were a considerable driver for profitability for these banks accounting for 16.5 percent of net interest income for the U.S.’s 5 largest banks in 2024. Looking at the entirety of the banking sector, IORB payments accounted for 16.1 percent of all net interest income of U.S. banks in 2024.
……….

Share of Foreign and Domestic Payments

While the proportion of IORB payments to foreign banks has decreased slightly since 2013, the gross amount in payments sent to foreign banks continues to grow substantially each year as the Fed has increased IORB rates. In 2019, prior to the pandemic, $13 billion in IORB payments were paid to foreign banks. Since 2022, however, the Fed has paid an average of $50 billion in IORB payments to foreign institutions and this number continues to grow.
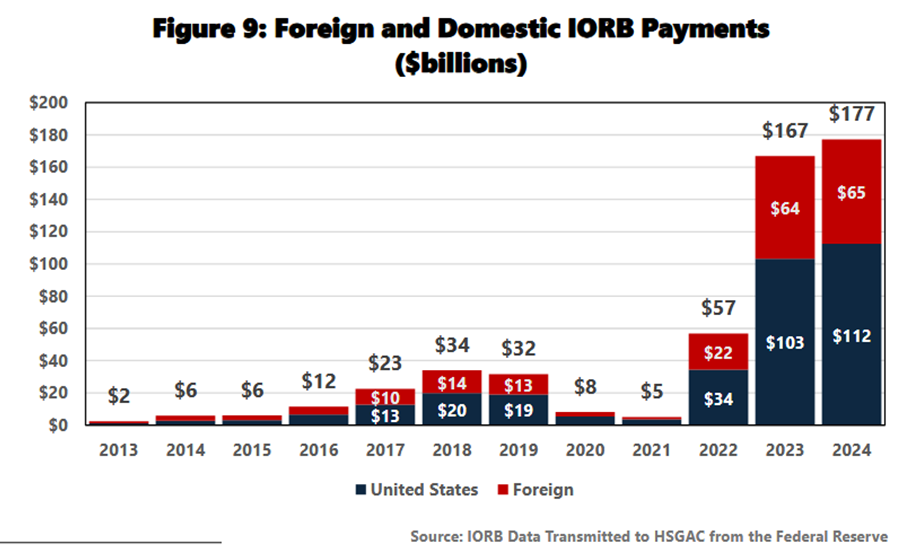
As IORB rates drastically increased in late 2021 and 2022, not only did domestic banks rush to park capital at the Fed, but foreign banks also seemed to inject dormant capital from their international banks into their U.S. subsidiary to take advantage of the more generous risk-free interest offered for excess reserves. The share of IORB payments jumped from 28.5 percent foreign banks (the lowest since 2013) to nearly 40 percent of payments….

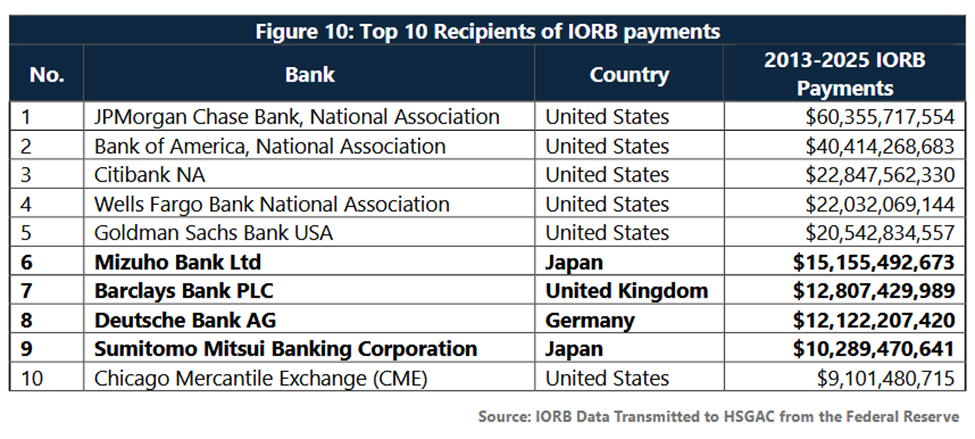
Many of the world’s largest banks have been the largest beneficiaries of IORB payments. Of top 10 recipients of IORB payments from July 2013 to July 2025, 4 are foreign banks (bolded), and 11 of the top 20 are foreign banks…:
IORB Payments as a Foreign Bank Subsidy

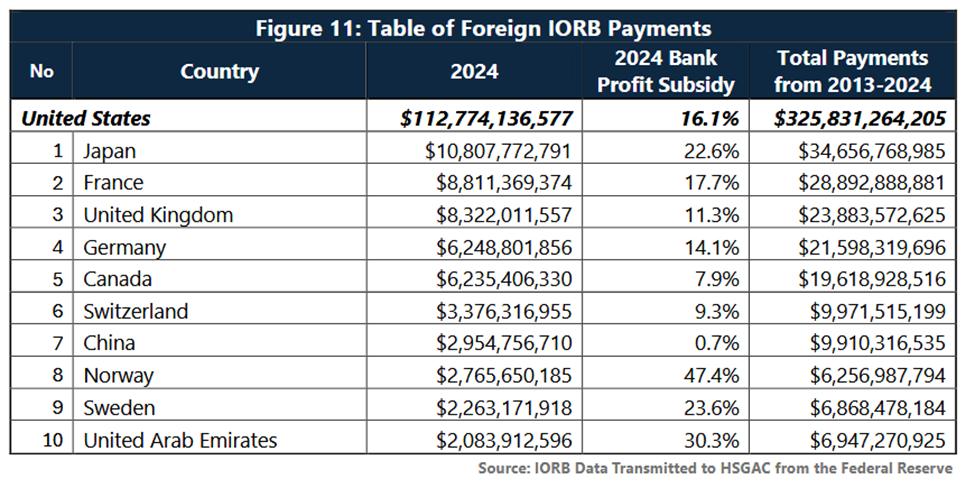
In 2024, while 16.1 percent of the U.S.’s banking sector’s net interest income comes at the expense of the taxpayer through IORB, 5 percent of all the participating foreign banks net interest income comes from the U.S. taxpayer. Figure 11 shows the top 10 benefitting nations and the percentage of bank profits  is subsidized by the U.S. taxpayer.

“Bank profit subsidy” reflects the percent of participating depository institution’s net interest income that is attributable to IORB payments from the Fed. Notably,

the American taxpayer has financed over 50 percent of Bahrain’s bank profits, 47 percent of Norway’s bank profits, and 22 percent of Japan’s bank profits…
Conclusion: Hundreds of billions of dollars for the taxpayer have been sent to foreign banks, hundreds of billions of dollars for the taxpayer have padded Wall Street’s profit margin, all without a single election, public debate, or independent audit. This is the first step in what should be a continued effort to audit the Federal Reserve.

Full report: https://www.tristatehomepage.com/wp-content/uploads/sites/92/2025/12/2025.12.08_IORB-Report-VFINAL.pdf

__________________________________

Again: “This costly means of conducting monetary policy has prevented the Fed from remitting profits to Treasury to pay down the Federal deficit and instead directed these funds into Wall Street’s profit margins.”

Federal budget deficits are skyrocketing as major Wall Street and foreign banks are being subsidized with hundreds of billions of dollars in Fed IORB payments.

Main Street America is paying a steep price for this ongoing kleptocratic snow job. The country is wallowing in debt… while the Fed is doling out hundreds of billions of dollars to pump up the profit margins of Wall Street’s largest banks and major foreign banks.

Main Street America Republicans have the plan to re-target Fed liquidity flows to pass through the hands of tax-paying U.S. citizens first, and then into the banking system (through Household debt service / elimination), and into America’s small business sector, and into savings and investing vehicles.

The Leviticus 25 Plan will generate federal budget surpluses of $37.303 billion each of its first five years of activation (2027-2031) and pay for itself entirely over the succeeding 10-15 years.

The Leviticus 25 Plan is a dynamic economic initiative providing direct liquidity benefits for American families, while at the same time scaling back the role of government in managing and controlling the affairs of citizens.  It is a comprehensive plan with long-term economic and social benefits for citizens and government.

The inspiration for this plan is based upon Biblical principles set forth in the Book of Leviticus, principles tendering direct economic liberties to the people.

The Leviticus 25 Plan – An Economic Acceleration Plan for America

$95,000 per U.S. citizen – Leviticus 25 Plan 2026 (43426 downloads )
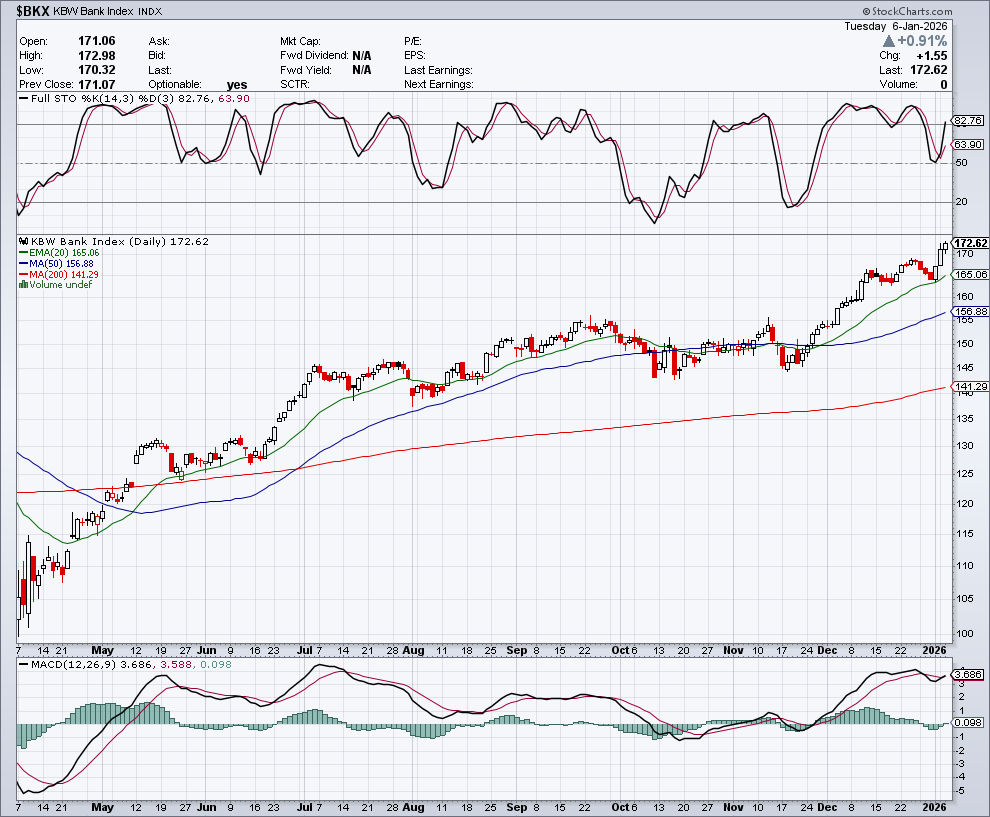
Large Money Center Banks Thriving In Slumping, Debt-strapped U.S. Economy. Enter America’s Reset Blockbuster: The Leviticus 25 Plan

The KBW Index – large national money center banks have been faring very well, in what is otherwise a burdensome and stifling economic climate for businesses, working-class citizens, states, and student loan borrowers.

The KBW Index includes 24 banking stocks representing the large U.S. national money centers, regional banks and thrift institutions. The largest banks in the Index include:
JP Morgan Chase & Co.
Bank of America Corporation.
Wells Fargo & Company.
Morgan Stanley.
Goldman Sachs Group, Inc. ( The)
Citigroup
Capital One Financial Corporation.
U.S. Bancorp.

________________________________

Meanwhile across America: Businesses, working-class citizens, states, and student loan borrowers are not faring well…

Bankruptcies are exploding across the economy, hitting small businesses and households. Few industries are immune. – Business Insider

By Natalie Musumeci | Dec 27, 2025

  • From corporate giants to mom-and-pop shops, bankruptcies are piling up across the US this year.
  • Large corporate bankruptcies have hit their highest level in 15 years.
  • “Bankruptcies seem to be kind of all over the place,” one veteran bankruptcy attorney said.

Bankruptcies aren’t just rising — they’re suddenly everywhere.

From billion-dollar giants to mom-and-pop shops to everyday individuals, bankruptcies are piling up across the US this year, with large corporate bankruptcies already hitting their highest level in 15 years.

The surge in bankruptcies highlights the growing financial pressures facing consumers and companies as costs climb amid a tougher borrowing environment….

Personal bankruptcies – In addition to big and small businesses, individual bankruptcies have also increased amid rising costs. Individual bankruptcy filings saw an 8% jump to 40,973 in November 2025, up from the 37,814 filings in November 2024, the data cited by ABI shows.

Full article: https://www.businessinsider.com/bankruptcies-across-economy-small-business-households-corporate-2025-12

__________________________________

Credit Card Interest Rates

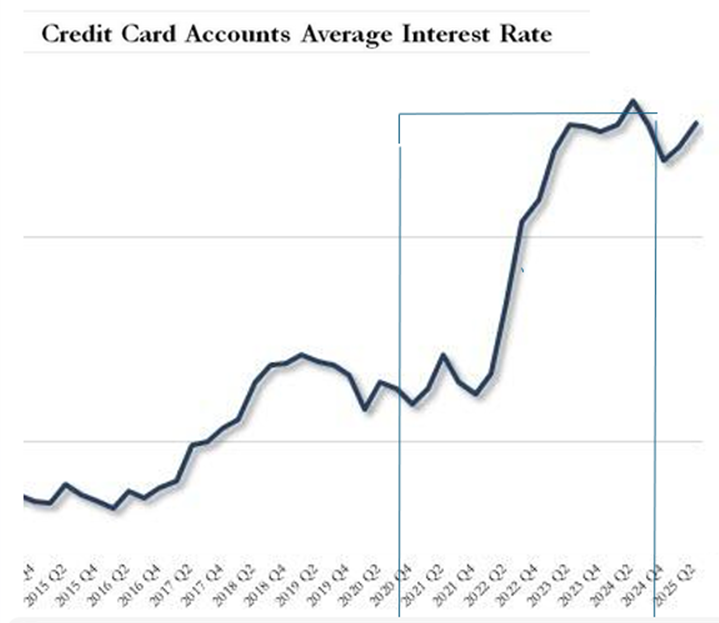
Federal Reserve’s latest consumer credit report (G.19): “Despite the 1.50% in rate cuts since last September, we can now confirm that rates on credit cards have gone… higher, as banks continue to bleed US consumers dry: at the start of 2025 the average rate on credit card accounts was 22.80%… and on Sept 30 the number was higher at 22.83%, just barely below the all time high of 23.37% set one year ago” (ZeroHedge).

______________________________________

States’ Recession Risk

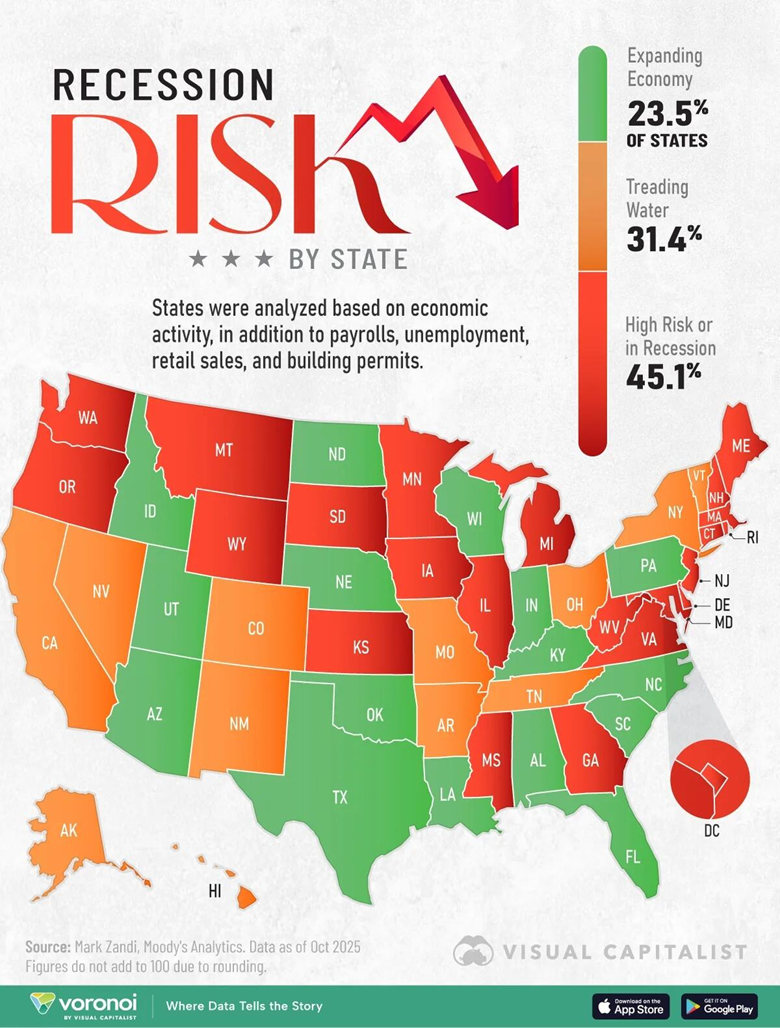
23 US States Are At High Risk Of (Or In) Recession Currently

ZeroHedge, Dec 22, 2025 – Excerpt:

In 2025, states responsible for about a third of U.S. GDP are in recession, or face high recession risk. Another third are expanding, including Florida and Utah, based on payrolls, employment, and other key economic data.

This graphic, via Visual Capitalist’s Dorothy Neufeld, shows recession risk by state in 2025, based on analysis from Mark Zandi, chief economist at Moody’s Analytics.

______________________________

Student Loan Stress

Education Department Has Rejected Over 300,000 Requests For Lower Student Loan Repayments

ZeroHedge, Dec 28, 2025 – Authored by Aaron Gifford via The Epoch Times, – Excerpt:

The U.S. Department of Education has so far denied requests from more than 300,000 existing student loan recipients seeking new repayment terms, according to documents filed in a federal court earlier this month.

The total debt carried by 43 million student loan borrowers currently totals about $1.62 trillion.

……………………..

On the Edge of a “Default Cliff”: New Survey Shows Student Loan Borrowers Are Struggling to Keep Up – Institute for College Access & Success

By Michelle Zampini, Dec 6, 2025 – Excerpt:

Beyond affordability, borrowers report mixed experience with servicers: more than half (61%) of borrowers report having communicated with their servicer to resolve an issue with their account; of those borrowers, three-quarters (75%) said they were able to work with their servicer to resolve the issue. However, nearly half of those borrowers (48%) reported facing long wait times to access help, one quarter (24%) said their servicer provided them with inaccurate information, and one in ten borrowers (11%) believe the balance shown on their account is incorrect.

These findings align with the limited data that ED has released so far this year. At the start of the pandemic pause in March 2020, 8.6 million borrowers were in default. While a portion of those borrowers resolved their default during the pause—either through the “Fresh Start” program or via having their debt discharged—new ED data released in November show that as of October 2025, more than 5.5 million borrowers with over $140 billion in outstanding federal student loans were in default.2 In addition, 1.17 million borrowers were 30-89 days delinquent, 1.56 million were 90-269 days delinquent, and 3.68 million were 270+ days delinquent.

____________________________

The Leviticus 25 Plan impartially grants U.S. citizens the same direct liquidity extensions that were provided to major U.S. and foreign banking concerns during the economic credit crisis of 2008-2010 and the Covid crisis of 2021-2022.

The Leviticus 25 Plan will cleanly and evenly eliminate massive amounts of public and private debt (mortgage debt, consumer debt, student loan debt). It will dramatically and powerfully restore financial security for millions of American families and small businesses.

Large money center banks, rather than receiving ‘hand-out’ liquidity flows direct from the Federal Reserve, will receive massive liquidity infusions that flow from the Fed direct to U.S. citizens, and then on into the banking system through opportunistic debt-elimination.

Excess cash reserves may then be directed by banks into the Treasury market to competitively lower interest rates.

The Leviticus 25 Plan is the most comprehensive, powerful economic acceleration plan anywhere on the planet.

The Leviticus 25 Plan is a dynamic economic initiative providing direct liquidity benefits for American families, while at the same time scaling back the role of government in managing and controlling the affairs of citizens.  It is a comprehensive plan with long-term economic and social benefits for citizens and government.

The inspiration for this plan is based upon Biblical principles set forth in the Book of Leviticus, principles tendering direct economic liberties to the people.

The Leviticus 25 Plan – An Economic Acceleration Plan for America

$95,000 per U.S. citizen – Leviticus 25 Plan 2026 (42435 downloads )

U.S. Starts Fiscal 2025 With $284.4 Billion October Deficit, Gross Interest Expense of $104.4 Billion – Highest on Record

Game Over DOGE: US Starts Fiscal 2025 With Record Budget Deficit, Shocking Interest Expense

ZeroHedge, Nov 25, 2025

Excerpts:

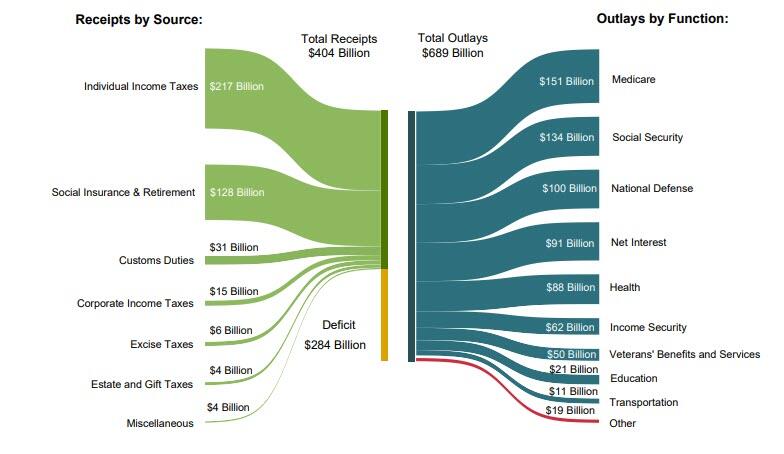
…..Earlier today, the Treasury published the October budget data, and it was ugly. Not all of it, mind you: tax receipts were actually quite solid: at $404 billion, consisting of $217 billion in income taxes and $128 billion in social security receipts…

… government revenues were actually a solid 23.7% improvement to the $326.8 billion collected in October 2024. Of course, that includes the now solid monthly contribution from Trump’s tariffs which in October added $31 billion to the tally.

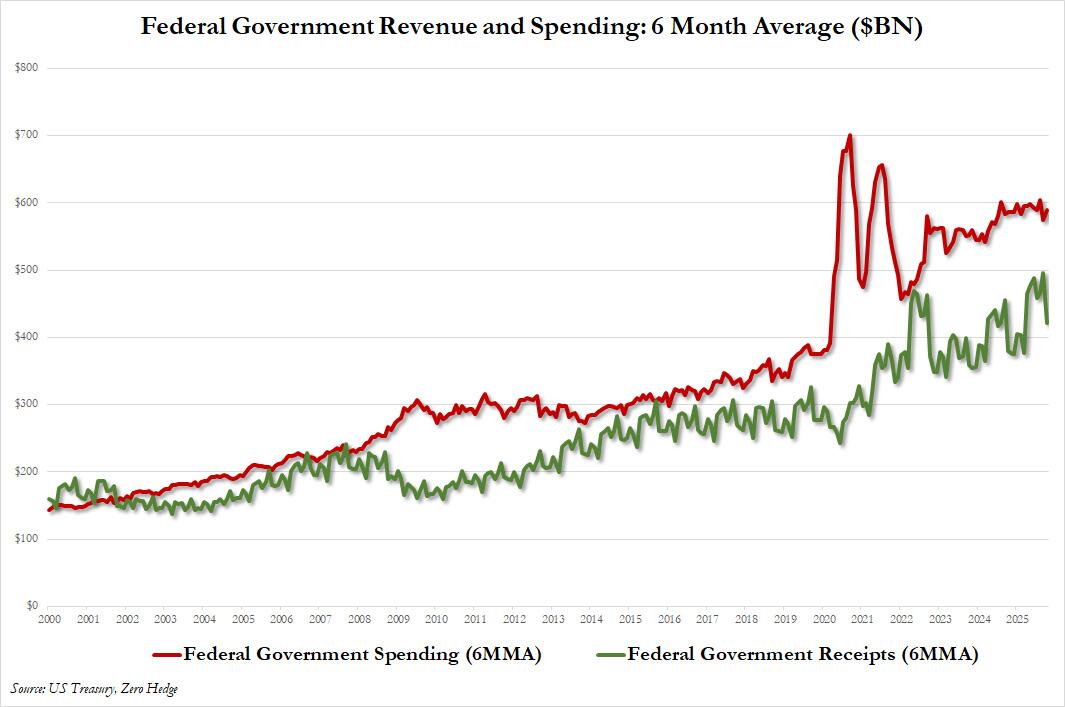
As usual, it was government spending that was the problem again, and at $688.7 billion, or over $22 billion per day, the October total was a 17.9% jump compared to the $584.2 billion spent a year prior. And just when the US was making some modest progress on merging the red (spending) and green (revenue) lines.

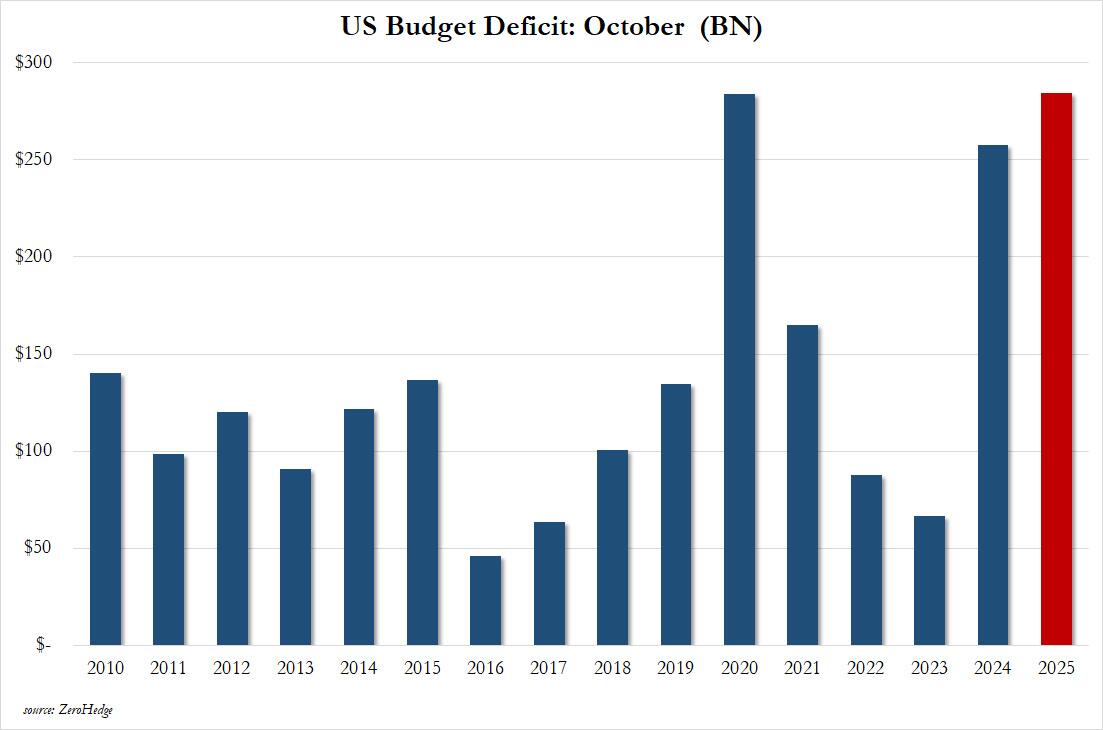
The combination of these two numbers resulted in a $284.4 billion deficit for the month of October, which was not only higher than the $257.5 billion deficit last October, but also higher than the record Covid budget buster of $284.1 billion in October 2020! 

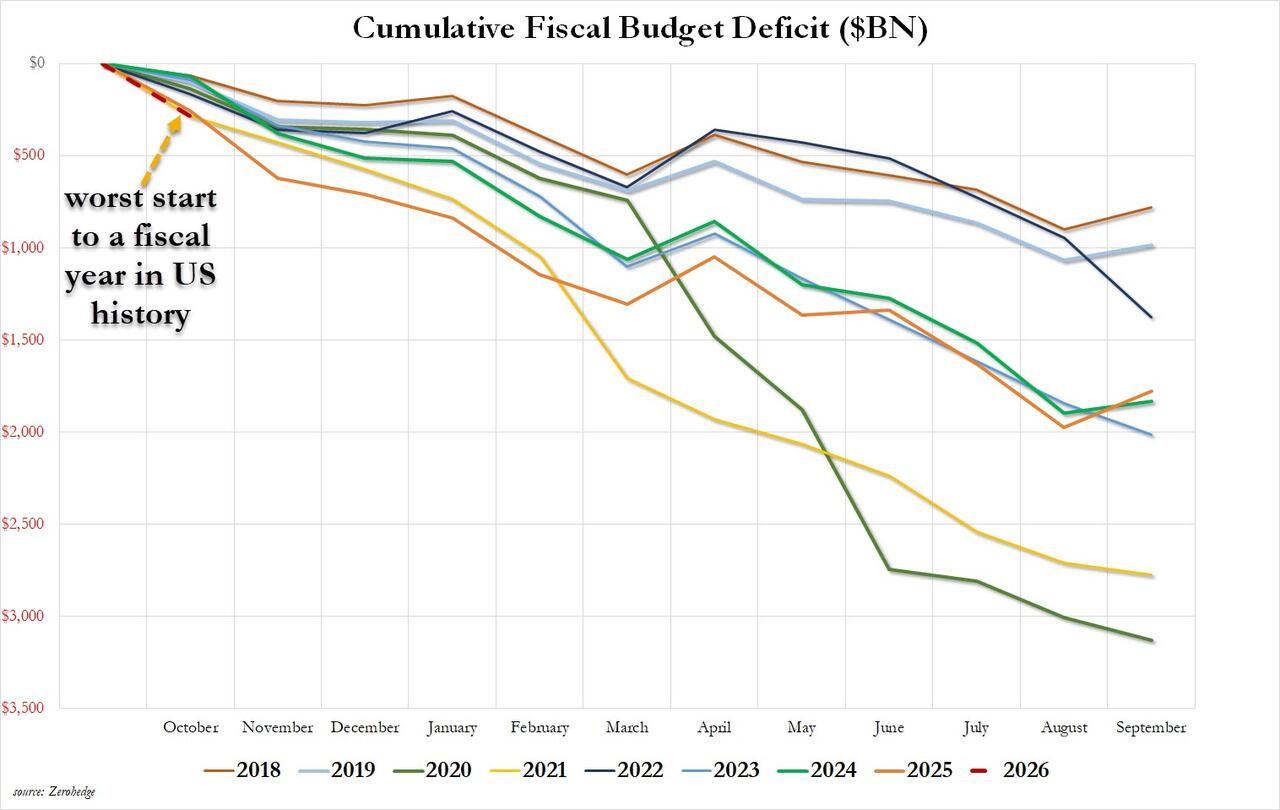
And since we are now (only) one month in fiscal 2026, we now have the worst budget-deficit start to a fiscal year in US history.

In other words, no matter what the official line is, DOGE has left the building. 

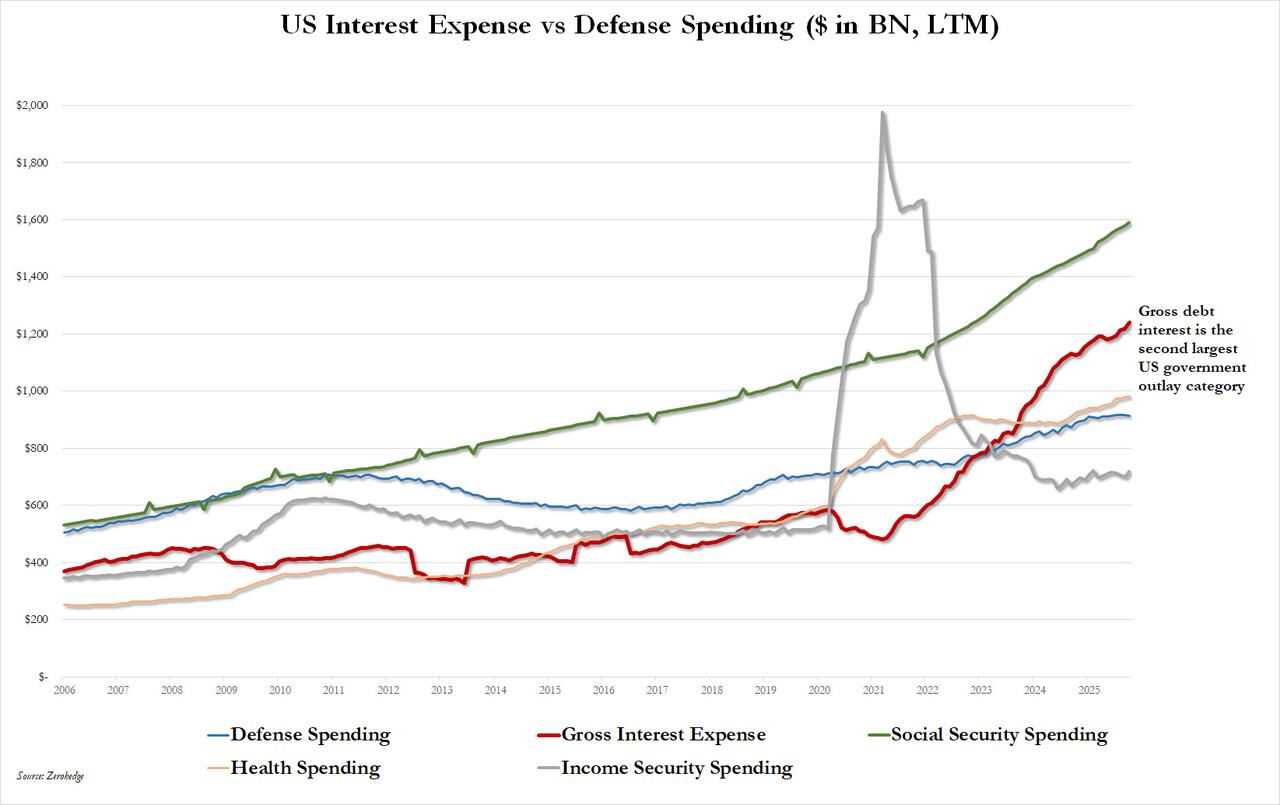
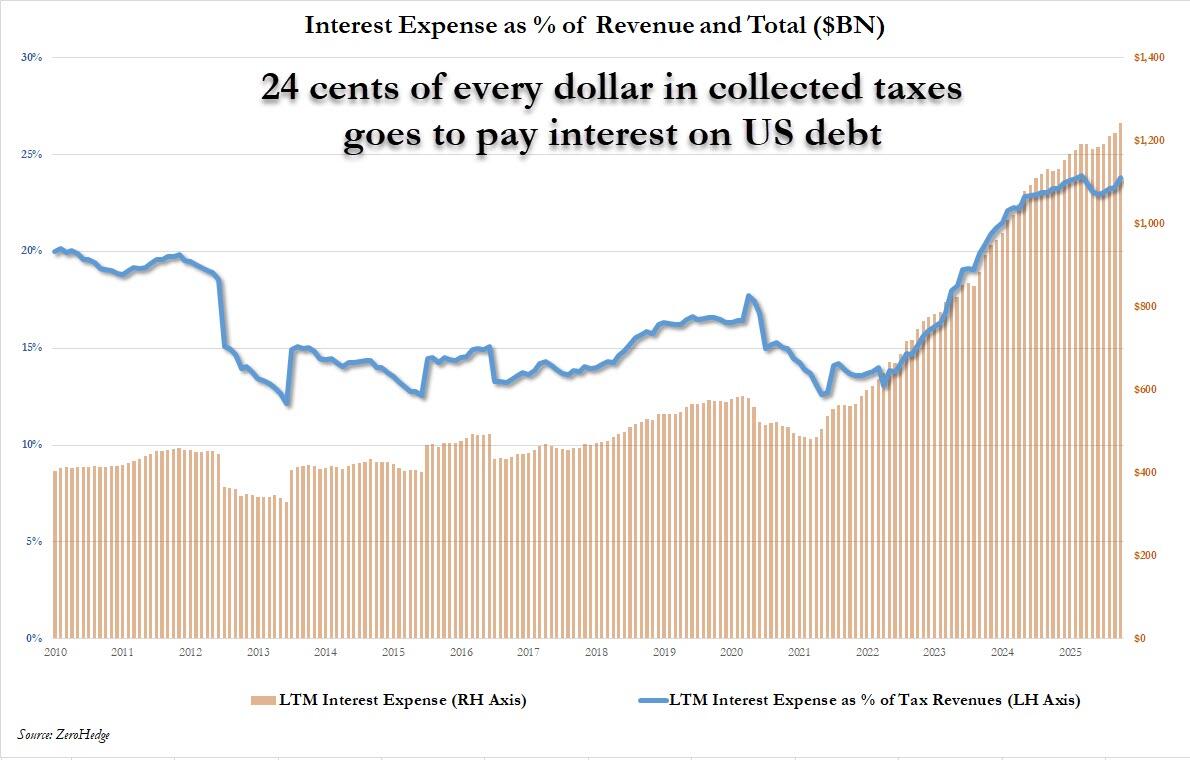
Taking a closer look at the causes of the October budget-busting deficit reveals the same usual suspects: spending across all major categories increased in October, but the most dramatic one was once again the relentless surge in the gross US interest, which is now a record $1.24 trillion in the last twelve months, and is rapidly approaching social security ($1.589 trillion LTM) as the largest source of government spending. 

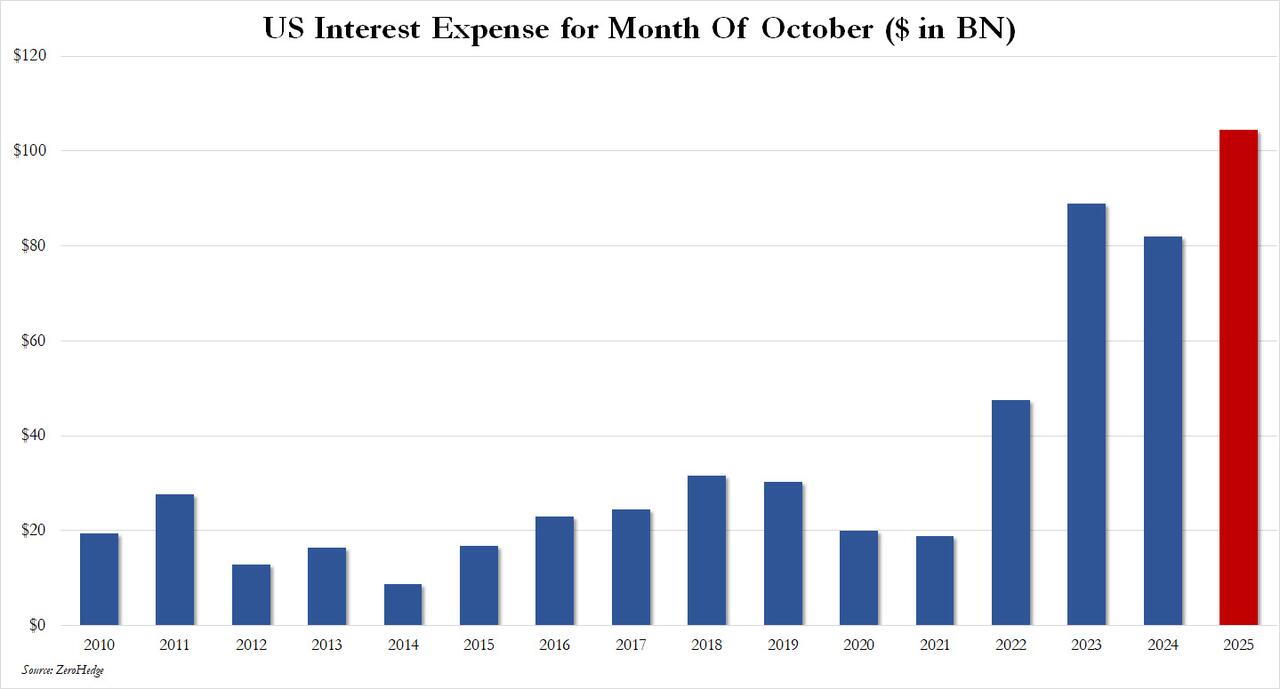
And here is the punchline: October gross interest was a record $104.4 billion, the highest for the month on record…

… and at $1.24 trillion in LTM interest expense, it means that 24 cents of every dollar in collected taxes goes to pay interest on the debt. 

Bottom line: after a brief period of irrational hope in early 2025 when Musk’s obsession with DOGE and cutting spending gave the US some hope that there just may some – very painful – way out of this Minsky Moment, we are not only back at square zero one and back on the fast-track to the debt-death of the United States, but the US fiscal picture has never been worse!

No wonder why in a recent public commentary, Musk fully agrees with us: the government is unfixable.

___________________________________________

Mr. Musk is wrong. “Government,” and America’s fiscal failures are indeed “fixable.’

The Leviticus 25 Plan is a dynamic economic initiative providing direct liquidity benefits for American families, while at the same time scaling back the role of government in managing and controlling the affairs of citizens.  It is a comprehensive plan with long-term economic and social benefits for citizens and government.

The inspiration for this plan is based upon Biblical principles set forth in the Book of Leviticus, principles tendering direct economic liberties to the people.

The Leviticus 25 Plan – An Economic Acceleration Plan for America

$95,000 per U.S. citizen – Leviticus 25 Plan 2026 (40947 downloads )

Millions of Americans Living ‘Paycheck to Paycheck’

Nearly 1 in 4 American households living paycheck to paycheck, report reveals

Lower-income families hit hardest as inflation grows faster than wages, Bank of America Institute data shows

By Eric Revell FOXBusiness

Excerpts:

The Bank of America Institute report found that almost 24% of households would be classified as living paycheck to paycheck so far in 2025, an increase of 0.3 percentage points from 2024 – although the growth rate is nearly three times lower than it was a year ago.

It defines living paycheck to paycheck as households spending over 95% of their income on necessities like housing, groceries, gas, utilities, internet plans, public transit and childcare. That leaves them with little or no leftover funds for savings or “nice-to-have” discretionary purchases. 

“Although the number of households living paycheck to paycheck is increasing this year, the pace of growth has slowed significantly,” Joe Wadford, an economist at the Bank of America Institute, told FOX Business. “That’s because it seems like a lot of the financial stress that has been increasing has been concentrated in these lower-income households as these families struggle to keep up with cost increases.”

Inflation has grown faster than middle- and lower-income households’ after-tax wages since January 2025, the Bank of America Institute found. 

That trend has led to the share of lower-income households living paycheck to paycheck rising to 29% this year, from 28.6% last year and 27.1% in 2023. Among middle- and higher-income households, there has been little to no increase in the proportion living paycheck to paycheck.

“For middle- and lower-income households, I think inflation is the primary driver. Especially this year, we’ve seen the gap between wages and expenses continue to widen for lower-income households,” Wadford said….

The report also found that wage growth for lower-income earners has been easing compared to higher-income counterparts since the start of 2025, after it rose faster in 2021-22, before cooling in 2023-24….

____________________________________

The Leviticus 25 Plan will lower the cost of living and relieve financial distress for millions of working, tax-paying American families through wide-ranging debt elimination dynamics and the billions of dollars in monthly savings in interest-related debt servicing obligations.

The Leviticus 25 Plan will grant direct liquidity transfers to qualifying U.S. citizens through a Fed-U.S.Treasury based Citizens Credit Facility – in the same way that it provided direct liquidity transfers to major Wall Street global financial institutions during the great financial crisis (2008-2010) and the Covid Criiss (2021-2022), that included none other than: Morgan Stanley, Citigroup, Bank of America, JP Morgan, Goldman Sachs, State Street, AIG, Merrill Lynch, Royal Bank of Scotland (RBS), Barclays, UBS, Deutsche Bank, BNP Paribas, and others…

The Leviticus 25 Plan is a dynamic economic initiative providing direct liquidity benefits for American families, while at the same time scaling back the role of government in managing and controlling the affairs of citizens.  It is a comprehensive plan with long-term economic and social benefits for citizens and government.

The inspiration for this plan is based upon Biblical principles set forth in the Book of Leviticus, principles tendering direct economic liberties to the people.

The Leviticus 25 Plan – An Economic Acceleration Plan for America

$95,000 per U.S. citizen – Leviticus 25 Plan 2026 (40818 downloads )

WalletHub: American Families “Drowning in Debt.” Main Street America Republicans’ Powerful Solution Loaded Up and Ready to Launch.

The Federal Reserve bailed out Wall Street financial firms (domestic and foreign) during the great financial crisis (2008-2010), to include: Morgan Stanley, Bank of America, Citibank, Goldman Sachs, JP Morgan, Merrill Lynch, AIG, State Street, UBS, BNP Paribas, Barclays, Deutsche Bank, Royal Bank of Scotland, and many others.

The Fed again stepped in to flush many of the same financial institutions with liquidity during the Covid crisis (2021-22).

It is now time to grand U.S. citizens the same direct access to liquidity that was so generously doled out to Wall Street.

It is now time to restore financial order in America: The Leviticus 25 Plan

_________________________________

Americans report strain from so reasing household debt

Total household debt increased to $18.59 trillion in the third quarter of 2025, or $990 billion below the all-time 2008 high of $19.57 trillion.

By Elyse Apel | The Center Square | Published: November 12, 2025

More than half of U.S. households say they’re struggling with debt, according to a new WalletHub survey.

Total household debt increased to $18.59 trillion in the third quarter of 2025, which is $990 billion below the all-time 2008 high of $19.57 trillion.

Still, debt is steadily rising for many, with more than two in five people expecting their household debt to increase in the next 12 months.

Chip Lupo, a writer and analyst for WalletHub, told The Center Square in an exclusive interview that the survey’s findings are very concerning.

“What stood out most to me about this survey is just how deeply Americans feel the weight of debt; not just financially, but emotionally and physically,” Lupo said. “More than half of households report struggling with debt; 36% feel ‘owned’ by credit card companies; and 38% say it affects their health. This combination of financial strain and personal stress is striking.”

The recently-released survey was done in conjunction with WalletHub’s Household Debt Report, which examined the latest economic data from the third quarter. Notably, the report found that the average American household had:

• $108,425 in mortgage debt

• $3,500 in home equity lines of credit debt

• $13,727 in auto loan debt

• $13,711 in student loan debt

• $10,227 in credit card debt

• $4,562 in other debt, which included personal loans and other financing

The survey sought to put these findings from the report in context. Across the nation, it found that American families are drowning in debt.

In total, 56% said their household is struggling with debt. Many don’t see an end in sight, with 46% anticipating they will still have debt when they die.

Credit card debt is causing the most strain for families, the survey found. In total, 46% of American households reported struggling with credit card debt the most, followed by mortgages at 23% and student loans at 13%.

Many pointed to high inflation and an ever-increasing cost of living as playing a role in their increasing debt.

“High inflation is seen as the primary driver of rising debt, and nearly half of Americans expect to carry debt to the grave,” Lupo said. “These figures highlight how critical it is for consumers to track their net worth and actively manage debt, especially credit card balances, as the survey shows that this is the most common source of financial stress.”

…………………………………………………………….

Where US Families Are Most Strained By Debt

ZeroHedge, Nov 01, 2025

Excerpt:

Americans are always worrying about debt: their own and their government’s.

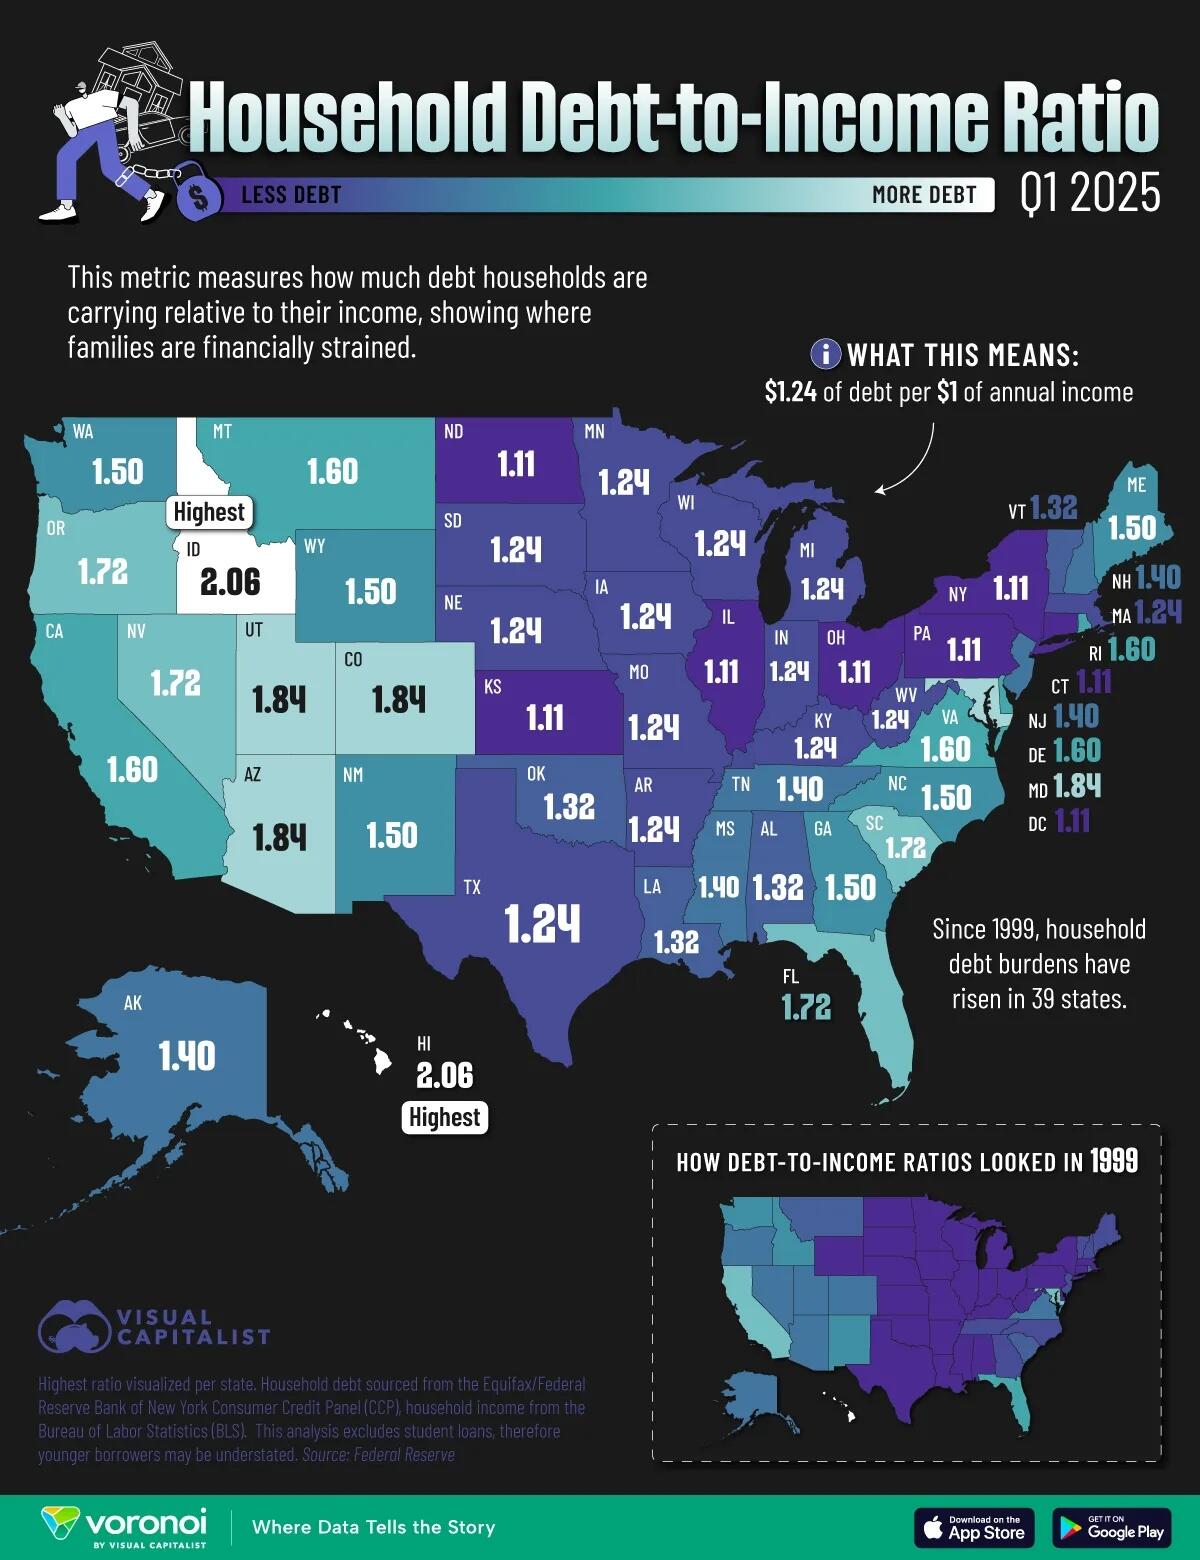
This visualization, via Visual Capitalist’s Pallavi Rao, maps each state by their household debt-to-income ratios (DTI) in Q1, 2025, revealing which states carry the heaviest burdens and which ones keep borrowing in check.

Data for this visualization comes from the Federal Reserve. The highest ratio is visualized per state.

ℹ️ Debt includes mortgages, autos, credit cards, etc., and excludes student loans. Income is based on unemployment insurance-covered wages, as reported to the Bureau of Labor Statistics.

Which States Carry the Most Debt?

Two states share the top spot: Idaho and Hawaii both post a DTI of 2.06, meaning households owe just over twice their annual after-tax income.

RankStateState CodeDebt-to-Income Ratio (2025)Debt-to-Income Ratio (1999)1999–2025 Change
1IdahoID2.061.500.56
2HawaiiHI2.062.060.00
3ArizonaAZ1.841.400.44
4ColoradoCO1.841.400.44
5UtahUT1.841.400.44
6MarylandMD1.841.720.12
7South CarolinaSC1.721.320.40
8NevadaNV1.721.400.32
9OregonOR1.721.400.32
10FloridaFL1.721.600.12
11DelawareDE1.601.110.49
12MontanaMT1.601.320.28
13Rhode IslandRI1.601.320.28
14VirginiaVA1.601.400.20
15CaliforniaCA1.601.72-0.12
16WyomingWY1.501.110.39
17GeorgiaGA1.501.240.26
18MaineME1.501.240.26
19North CarolinaNC1.501.240.26
20New MexicoNM1.501.500.00
21WashingtonWA1.501.500.00
22MississippiMS1.401.110.29
23New HampshireNH1.401.240.16
24New JerseyNJ1.401.240.16
25TennesseeTN1.401.240.16
26AlaskaAK1.401.320.08
27AlabamaAL1.321.110.21
28LouisianaLA1.321.110.21
29OklahomaOK1.321.110.21
30VermontVT1.321.240.08
31ArkansasAR1.241.110.13
32IndianaIN1.241.110.13
33IowaIA1.241.110.13
34KentuckyKY1.241.110.13
35MassachusettsMA1.241.110.13
36MichiganMI1.241.110.13
37MinnesotaMN1.241.110.13
38MissouriMO1.241.110.13
39NebraskaNE1.241.110.13
40South DakotaSD1.241.110.13
41TexasTX1.241.110.13
42West VirginiaWV1.241.110.13
43WisconsinWI1.241.110.13
44ConnecticutCT1.111.110.00
45District of ColumbiaDC1.111.110.00
46IllinoisIL1.111.110.00
47KansasKS1.111.110.00
48New YorkNY1.111.110.00
49North DakotaND1.111.110.00
50OhioOH1.111.110.00
51PennsylvaniaPA1.111.110.00

…check out Visualizing Government Debt-to-GDP Around the World on Voronoi, the new app from Visual Capitalist.

___________________________________________

The Leviticus 25 Plan is the one and only comprehensive economic acceleration plan in the world with the raw power to eliminate massive tracts of family debt and restore self-reliance and financial security for millions of qualifying American families.

It is also the only plan that can restore financial order within the U.S. federal government and the state governments of all 51 states.

The Leviticus 25 Plan will also generate an average $36.568 billion in federal budget surpluses over each of the first five years of activation (2026-2030) – versus projected $2 trillion deficits.

The Leviticus 25 Plan – An Economic Acceleration Plan for America

$95,000 per U.S. citizen – Leviticus 25 Plan 2026 (40186 downloads )

Food Stamp (SNAP) Clean Up Time – Lifting People Up Out of Poverty the Right Way, and Saving America Billions…

The Leviticus 25 Plan would lift millions of working-class, tax-paying American families up out of poverty – and eliminate the ever-growing dilemma of food lines and dependence upon government-based food handouts.

……………………………………………

Food Stamps To Be Paused For 42 Million Americans: What To Know…

ZeroHedge, Oct 29, 2025 – Excerpts:

Food stamps are set to be paused on Nov. 1 because of the government shutdown.

Some 42 million Americans will not receive benefits through the Supplemental Nutrition Assistance Program (SNAP) until Congress approves new funding, according to federal officials, although some states have taken steps to intervene.

As Ryan McMaken details below, via The Mises Institute, according to the Treasury Department’s report on federal spending for fiscal year 2025, total spending on food stamps—also known as the Supplemental Nutrition Assistance Program (SNAP)—was $106 billion for the twelve-month period ending September 30.

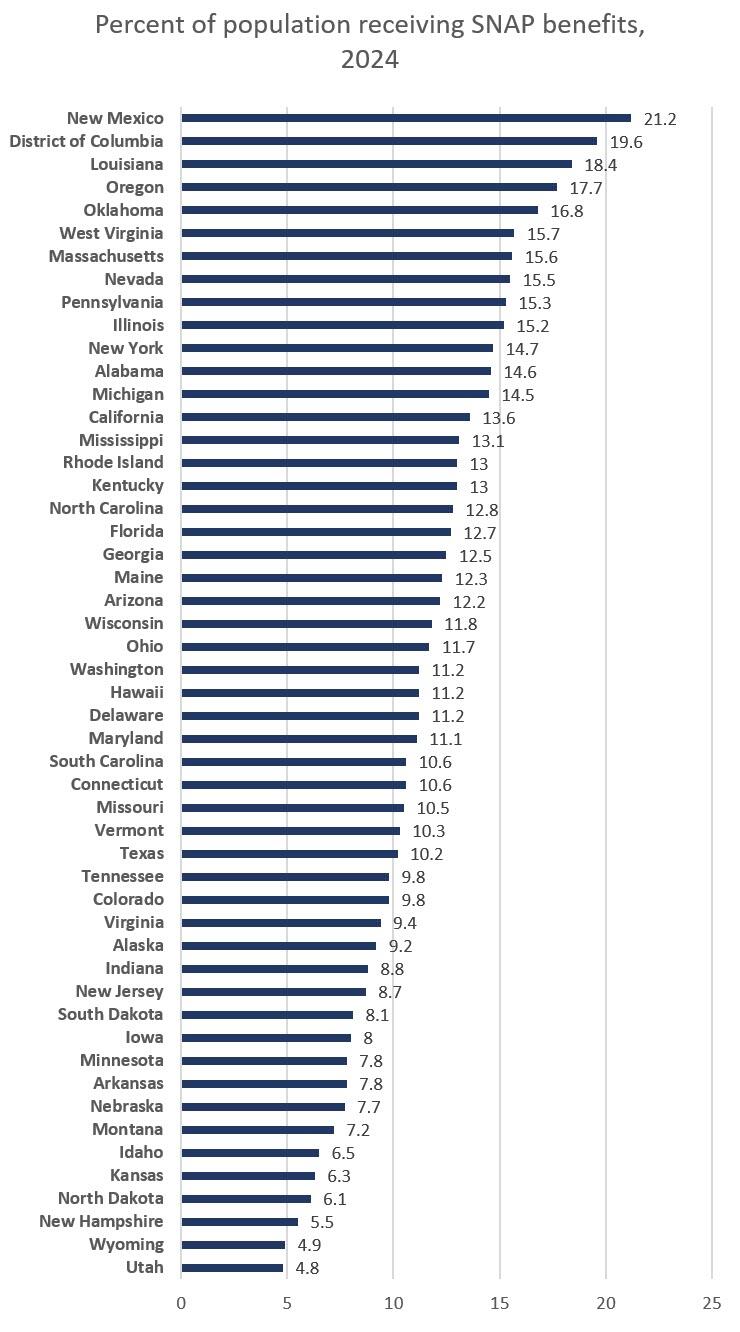
Nationwide, the total percentage of the population receiving food stamps can vary significantly by state, and region. Measured state-by-state, we find that more than one in five residents of New Mexico receive food stamps. In Utah, on the other hand, fewer than one in twenty receive food stamps. 

………………………………………………………………..…………………

Mercatus Center | George Mason University | May 13, 2025

Reducing Waste and Fraud in SNAP

Why SNAP fraud persists—and how to stop it

By Keith Hall
Excerpts:

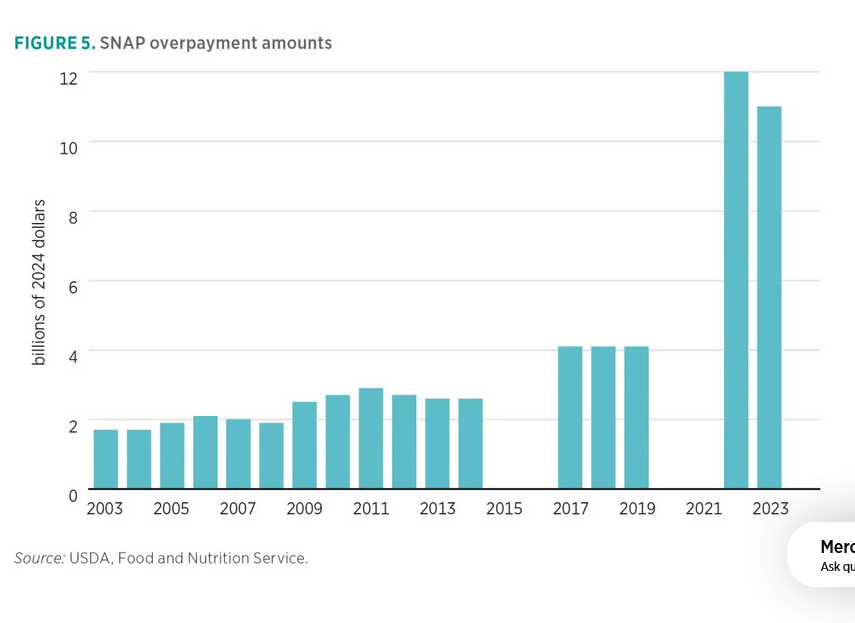
By 2023, the pandemic had pushed the national SNAP program error rate to nearly 12 percent, with overpayments amounting to about 10 percent of that figure. At the state level, overpayment rates were as high as 57 percent for Alaska. Even before the increase in the pandemic-era rates, the national overpayment rate had been rising rapidly: While it was just a little over 2 percent in 2012, the national overpayment rate hit 6 percent in 2019, before the pandemic. In dollar terms, as of December 2024, SNAP overpayments are up to $10 billion per year, and much of this amount is from benefit trafficking, which now costs $1.3 billion annually.

Nonbenefit costs to the federal government

In addition to contributing to state administrative expenses, the federal government covers other, nonbenefit costs associated with SNAP. First, the FNS reviews the states’ administration of the program in accordance with federal requirements. The federal government also supports state expenses for nutrition education programs, employment and training programs, benefit and retailer redemption and monitoring, payment accuracy, electronic benefits transfer (EBT) systems, program evaluation and modernization, program access, and health and nutrition pilot projects.

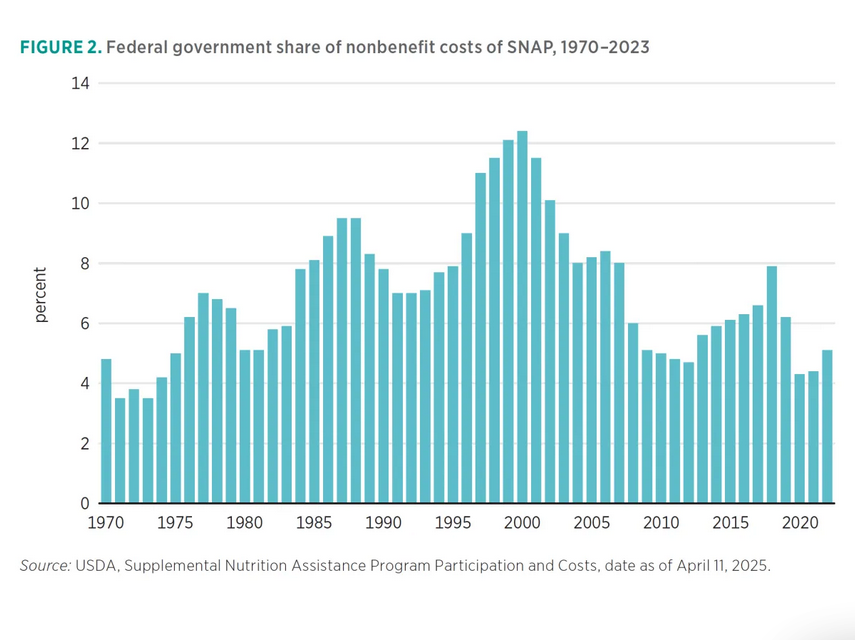
The share of total federal spending on nonbenefit costs was about $6 billion in FY 2023, or 5 percent of the total costs (see figure 2).[3] SNAP administrative expenses vary quite widely by state.[4] For example, in FY 2016 average administrative expenses varied from $89 per case in Florida to $848 per case in Wyoming. However, there is little understanding of these differences, as this variation does not seem to be explained by economic conditions or caseload levels.

Overpayments have always dominated the program error rate. In 2023, for example, they outpaced underpayments six to one… in FY2023, SNAP overpayments totaled $10.7 billion, but recovery of overpayments was just $389 million, or less than 4 percent.[13]

Despite increased efforts to curtail waste, there has been no evidence of anything but increases in overpayments since FY 2013. Furthermore, there is no comprehensive measure of fraud in the program, but taxpayer dollars are lost whether overpayments are fraudulent or just errors. Because of the high cost of the program, these overpayment rates have certainly cost the government tens of billions of dollars (see figure 5).

SNAP Fraud
Trafficking of SNAP benefits
Problems specifically related to the use of EBT cards
Retailer application fraud
Errors and fraud by households
Errors and fraud by state agencies

__________________________________________

The vast majority of federal and state entitlement programs, SNAP and TANF in particular, are rife with waste and fraud.

There is one comprehensive economic plan in America with the raw power to wipe out hundreds of billions of dollars in these annual losses – while at the same time lifting millions of U.S. citizens up out of the ranks of poverty.

The Leviticus 25 Plan is a dynamic economic initiative providing direct liquidity benefits for American families, while at the same time scaling back the role of government in managing and controlling the affairs of citizens.  It is a comprehensive plan with long-term economic and social benefits for citizens and government.

The inspiration for this plan is based upon Biblical principles set forth in the Book of Leviticus, principles tendering direct economic liberties to the people.

The Leviticus 25 Plan – An Economic Acceleration Plan for America

$95,000 per U.S. citizen – Leviticus 25 Plan 2026 (38545 downloads )

Keenan: “The Hidden Architecture of Debt” – How Private Banks Captured the Global Economy.

There is one dynamic blueprint to rebalance the U.S. economy in favor ‘non-debt based’ money creation: The Leviticus 25 Plan.

…………………………………

The Hidden Architecture Of Debt: How Private Banks Captured The Global Economy

ZeroHedge, Oct 27, 2025 – Authored by Mark Keenan via RealityBooks.com,

Select Excerpts:

Introduction: Why Money Power Matters

A century of central banking and commercial credit has normalized a simple but profound fact: most new money is created when banks make loans. As former U.S. Treasury Secretary Robert B. Anderson put it in 1959, when a bank issues a loan, it credits a deposit that did not exist the moment before; the new deposit is “new money.” In practice, this means the money supply expands primarily through private lending, not public issuance.

That mechanism is turbocharged by fractional-reserve banking and today by capital-based banking rules: banks do not lend out pre-existing savings one-for-one; they expand deposits by creating credit. Interest is attached to that credit, meaning the system requires continual new borrowing to service past borrowing. If credit creation slows materially, defaults rise, asset prices wobble, and political pressure mounts to “stimulate” again. In short, we live inside a treadmill that is far more credit-driven than most civics textbooks admit.

…………………………..

Modern banking’s political leverage grew alongside institutions like the Bank of England and, later, the U.S. Federal Reserve (established in 1913). Whatever the intention of their founders, central banks now sit at the junction of state and finance: they are publicly mandated yet operationally insulated (and privately owned), coordinating liquidity to stabilize the system while commercial banks originate most money-like claims.

This hybrid design has real consequences. It allows a small circle of decision-makers to set the price of money (interest rates), backstop private balance sheets in crises, and influence fiscal choices by making some policies financially easy and others expensive. Former Fed Chair Alan Greenspan once emphasized the institution’s independence; the flip side of that independence is low democratic visibility over choices that shape every mortgage, job market, and public budget.

Beyond national central banks lies the Bank for International Settlements (BIS) in Basel — often called the “central bank of central banks.” Through standards (Basel accords) and coordination, it helps align global banking rules. Critics argue this produces a technocratic layer of control over national economies with little public oversight. Whether one views that as prudent stewardship or as democratic deficit, it underscores a theme: the architecture of money governance is largely opaque to the public it governs.

……………………..

Critics like Roy Madron, John Jopling, and John Scales Avery have argued that this growth-dependency crowds out other goals: equitable distribution, environmental stewardship, and cultural stability. It also explains why mainstream debates often avoid the root structure and instead focus on the speed of the treadmill…

………………….

When money is predominantly debt, interest is not a side note; it is a structural tax on all who need money to transact. Banks, by creating credit, collect streams of interest that compound through the system. Meanwhile, inflation — the dilution of purchasing power — often becomes a necessary byproduct of keeping debt-loads serviceable. In practice, inflation acts as a stealth transfer from savers and wage earners to those closer to the spigot of new money (large financial institutions and asset owners).

This is not an argument to abolish credit; modern economies need flexible financing. It is an argument to name the trade-offs honestly. When we call monetary loosening a “stimulus,” we should also disclose who absorbs the loss in purchasing power and who gains from asset inflation. When we raise rates to “fight inflation,” we should admit the cost in jobs, bankruptcies, and public budgets. Stability is never free; it is reallocated volatility.

…………………..

Beyond national systems lies a web of global coordination — standards, swap lines, and lender-of-last-resort arrangements that knit economies together. Institutions such as the BIS, the IMF, and development banks shape the terms of liquidity and restructuring. Supporters say this is necessary to prevent contagion; critics counter that it allows a transnational financial class to set conditions on democratic societies in moments of maximum vulnerability.

Both views can be true. But whichever side you take, the outcome is similar: creditors hold leverage, and policy follows balance-sheet realities. The deeper the debt and the tighter the markets, the narrower the options for governments and citizens. This is not a conspiracy; it is a design choice we rarely discuss.

………………

Conclusion: Seeing the Machine

If you remember only one thing, let it be this: money is not neutral. How it is created, who controls its issuance, and what claims attach to it determine the shape of our economies and the boundaries of our politics. We can disagree about the best reforms, but we can no longer afford civic illiteracy about the monetary plumbing that governs our lives.

In a healthy society, the architecture of money would be a public conversation, not a specialist’s secret. Until then, the treadmill will keep turning — and those closest to the controls will keep deciding how fast the rest of us must run.

Full article: https://www.zerohedge.com/geopolitical/hidden-architecture-debt-how-private-banks-captured-global-economy

*  *  *

Mark Keenan is a former United Nations technical expert and the author of The Debt Machine: How Private Banks Engineered Global Control and Climate CO₂ Hoax: How Bankers Hijacked the Environment Movement. His work examines how global finance and policy networks shape the modern world behind the scenes.

______________________________________

The Leviticus 25 Plan corrects the imbalances in America’s debt-based money creation by granting millions of hard-working, tax-paying U.S. citizens the same direct liquidity extensions that were so generously provided to major U.S. and foreign banking concerns during the 2008-2010 great financial crisis, and again during the 2021-2023 Covid crisis.

The Leviticus 25 Plan – An Economic Acceleration Plan for America

$95,000 per U.S. citizen – Leviticus 25 Plan 2026 (38442 downloads )

BIG Government and the Sovereign Debt Crisis

“Big government means low growth, high taxes, weak real wages, and a persistent productivity drag..”

Solution: There is one economic plan with the raw firepower to reignite economic growth, reduce taxes, generate ‘real wage gains,’ and spur productivity — The Leviticus 25 Plan

………………………………………………………

The “Triumph Of Big Government” Created The Current Sovereign Debt Crisis

ZeroHedge, Oct 22, 2025 – Authored by Daniel Lacalle,

Excerpts:

A few years ago, The Economist published an issue called “The Triumph of Big Government,” highlighting the rise of government intervention as the main driver of economic recovery and growth. The years of budget and deficit control were over. Mainstream economists hailed the decisive action of governments in developed nations, committed to spending to boost growth and abandoning the old “austerity” principles.

Only a few years later, The Economist publishes an issue titled “The Coming Debt Emergency,” mentioning the enormous deficit and debt problems in France, the United Kingdom, Japan, and the United States.

What happened? How can long-term bond yields rise when central banks are cutting rates? How did government debt lose its place as a reserve asset? Easy. Developed economies’ governments of all colours, from Biden and Sunak to Macron and Ishiba, bought the MMT fallacy that “deficits do not matter” and “sovereign nations can issue all the debt they need without risk.” Virtually all international bodies hailed statism as the global solution. However, in 2022, global central banks and investors started abandoning sovereign debt as a reserve asset and decided to add gold.

Developed nations have surpassed the three limits of indebtedness: the economic, fiscal and inflationary limitations. When more public debt creates lower economic and productivity growth, the economic limit has been surpassed. When interest expenses and deficits continue to rise despite rate cuts and higher taxes, the fiscal limit collapses. Additionally, when governments become addicted to issuing more debt in any part of the cycle, with diminishing investor demand, inflation becomes persistent.

No one really believes developed nations’ governments will control their public finances, and constant tax hikes and excessive regulation have choked the productive economy.

Employment is showing the negative effect of the “triumph of big government”. Bloating government spending may disguise GDP but does not create jobs.

Even as government spending continues to artificially elevate headline GDP figures, global labour markets are showing weakness. According to S&P Global’s October 2025 PMI Bulletin, the global economy continues to show headline growth, but employment growth has stalled, and productivity improvement has declined sharply.

S&P Global’s global composite PMI stood at 52.4 in September, its lowest level in three months. Companies are attempting to manage high taxation and regulatory burdens, resulting in stagnant employment levels and output growth. Employment was broadly flat across both manufacturing and services sectors, a sign of declining confidence and cost-saving across advanced economies.

The eurozone is a key example of how big government destroys employment growth, real wage improvements and investment. The modest improvement in activity comes with a decline of hiring and investment. The United Kingdom’s tax hikes and net zero policies have decimated the industry and obliterated employment growth….

Government spending and persistent inflation bloat nominal growth, while real economic productivity and private labour opportunities deteriorate. The erosion of value-added generated by the productive economy is alarming. Considering that major governments are borrowing heavily to fund what they call stimulus measures, and they refuse to reduce current spending, GDP figures are being inflated by debt-financed public sector demand.

This labour market stagnation highlighted by S&P Global coincides with a significant slowdown in real wage growth. Although headline CPI has eased in most advanced economies, real inflationary pressures are elevated and continue to erode disposable income even using official CPI figures. This situation leads to weak real consumption and worsening demographic trends.

Big government means low growth, high taxes, weak real wages, and a persistent productivity drag. Malinvestment and excessive government intervention are now the norm in major economies. SP Global explains that “the most interest rate–sensitive sectors, such as manufacturing and construction, account for a smaller share of economic activity in advanced economies than in the past.” However, the problem is not just interest rates but rising taxes and insurmountable regulations that dampen activity in high multiplier sectors.

The 2030 agenda, along with the so-called green regulations and net zero policies, has resulted in capital misallocation and distortions in policy. Thus, productivity gains are increasingly limited to digital and financial sectors.

Fiscal expansion now drives most of the headline economic activity in developed nations with negative side effects everywhere. The debt service burden is crowding out productive expenditure, high taxes limit investment and hiring, and regulation makes the economy stagnant. As sovereign yields climb, countries like France and the UK are already facing “vicious cycles” of slower growth and higher financing costs.

The reader may think that this is the result of incompetence and malinvestment, and if governments spent wisely and invested in productive activities, all would be fine. No. Central planning never works, even if there are some allegedly beneficial intentions. Keynesianism and social democracy always fail. Why are governments not worried? Because they can raise your taxes and present themselves as the solution.

The solution is simple. Less government means more growth.

___________________________________

Again: “Big government means low growth, high taxes, weak real wages, and a persistent productivity drag..”

“…constant tax hikes and excessive regulation have choked the productive economy.”

“The solution is simple. Less government means more growth.“

………………………………..

And that solution is here – loaded up and ready to launch…

The Leviticus 25 Plan is a dynamic economic initiative providing direct liquidity benefits for American families, while at the same time scaling back the role of government in managing and controlling the affairs of citizens.  It is a comprehensive plan with long-term economic and social benefits for citizens and government.

The inspiration for this plan is based upon Biblical principles set forth in the Book of Leviticus, principles tendering direct economic liberties to the people.

The Leviticus 25 Plan – An Economic Acceleration Plan for America

$95,000 per U.S. citizen – Leviticus 25 Plan 2026 (38218 downloads )

Extreme Poverty Across the U.S. — and the One and Only Economic Plan in America to Lift People Up Out of It.

“No society can surely be flourishing and happy of which by far the greater part of the numbers are poor and miserable.”  – Adam Smith

…………..

Mapping Extreme Poverty Across All American States

ZeroHedge, Monday, Oct 06, 2025 – 06:20 PM

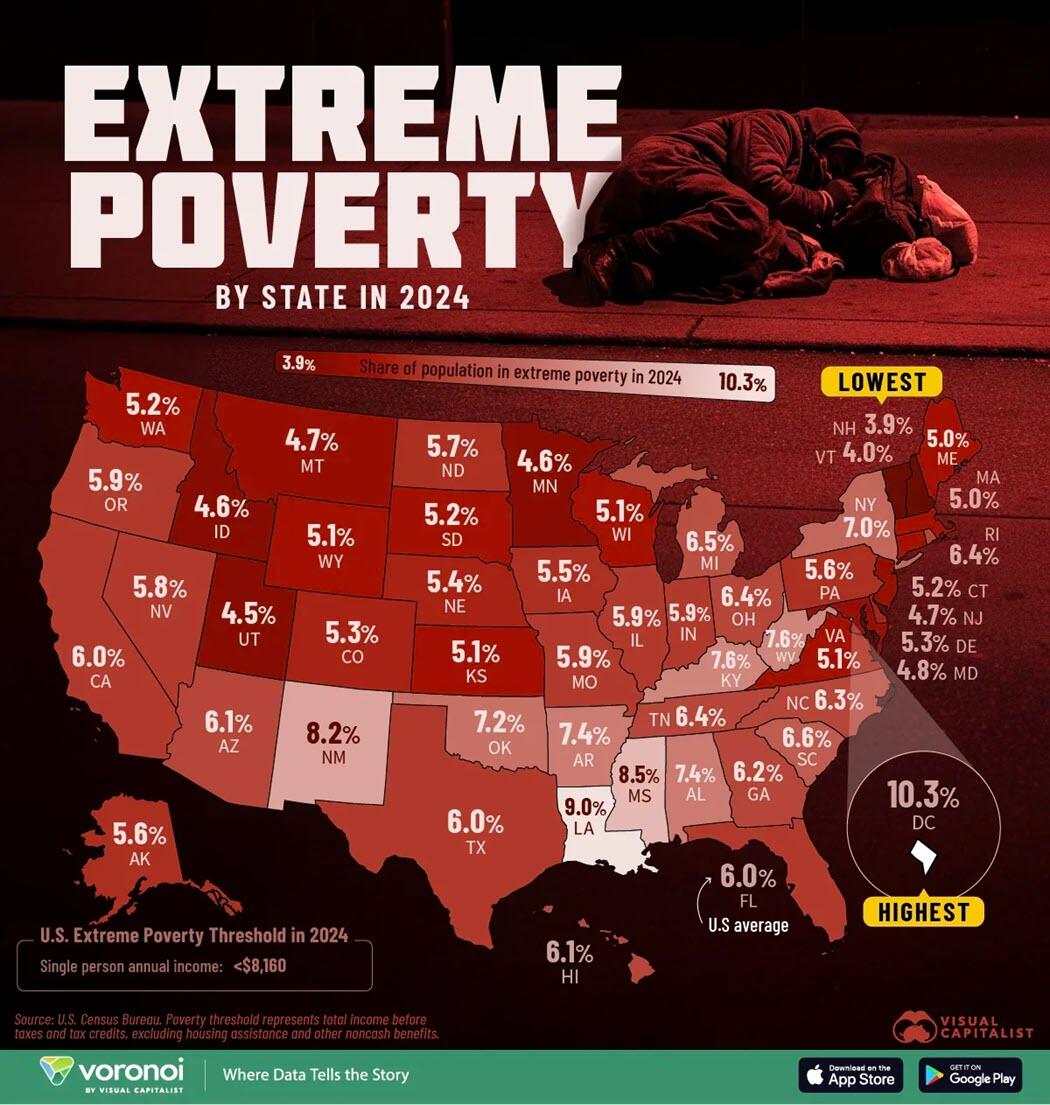
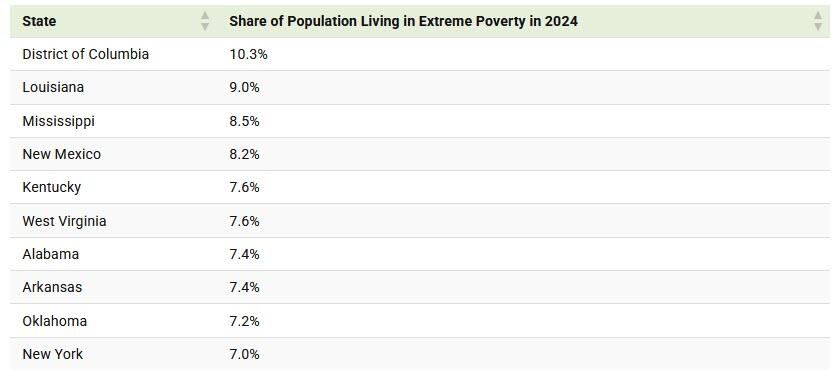
In 2024, 6% of the U.S. population lived in extreme poverty, equal to 20.4 million people.

While there are different definitions of extreme poverty, this is represented as those earning less than $8,160 in annual income, or half of the poverty line. As the federal budget makes cuts to food assistance and healthcare, levels of extreme poverty run the risk of worsening even further.

This graphic, viaVisual Capitalist’s Dorothy Neufeld, shows the share of each state living in extreme poverty in 2024, based on data from the U.S. Census Bureau.

Washington D.C. Has the Highest Level of Extreme Poverty

Last year, more than one in 10 residents of the nation’s capital lived in extreme poverty. 

Going further, economic hardship disproportionately impacts people of color in Washington D.C., with one in three black children living in poverty between 2019 and 2023, on average.

As we can see, Southern states also rank among the most impoverished. In Louisiana, 9% of residents live in extreme poverty, and on average, 18.9% lived below the poverty line between 2021 and 2023.

Meanwhile, 7% of New York’s population are extremely impoverished, equal to an estimated 1.4 million people.

On the other end of the spectrum is New Hampshire with the lowest rate nationally, at 3.9%. The Granite State benefits from a stable job market, low unemployment, and a strong education system. Paired with relatively affordable healthcare, these factors contribute to higher living standards for its residents, reducing the risk of poverty.

___________________________________

The Leviticus 25 Plan is the one plan in America with the raw, irresistible power to lift millions of qualifying U.S. citizens up out of poverty and back on the road to living productive lives.

The Leviticus 25 Plan is a dynamic economic initiative providing direct liquidity benefits for American families, while at the same time scaling back the role of government in managing and controlling the affairs of citizens.  It is a comprehensive plan with long-term economic and social benefits for citizens and government.

The inspiration for this plan is based upon Biblical principles set forth in the Book of Leviticus, principles tendering direct economic liberties to the people.

The Leviticus 25 Plan – An Economic Acceleration Plan for America

$95,000 per U.S. citizen – Leviticus 25 Plan 2026 (37306 downloads )

‘Obamacare Sweeteners’ Defrauding Taxpayers and ‘Poisoning Budget Negotiations’

Highlights:

“A whopping 40 percent of enrollees in fully subsidized plans had no claims in 2024. In 2024 alone, taxpayers sent at least $35 billion to insurers for people who paid no premiums and never used their plan”…

“COVID opened the door for massive waste, fraud, and abuse of government programs, like the billions in fraud and abuse allowed by the ‘temporary COVID’ enhanced Obamacare subsidies“…

_________________________________________________

The Obamacare Sweeteners Poisoning Budget Negotiations

ZeroHedge, Friday, Sep 26, 2025 – Authored by James Varney via RealClearInvestigations,

Halloween could come early this year. The Democrats have named their price to avoid a government shutdown come October – an additional $350 billion for healthcare over the next decade. Critics say a big chunk of that money may go to ghosts.

At issue are the generous subsidies the Biden administration created for Affordable Care Act policies, sweeteners that are slated to expire in December. Making healthcare essentially free for millions of Americans, those policies have skyrocketed enrollment in Obamacare plans. But a recent study found they have also sparked a curious phenomenon: an estimated 12 million enrollees “without a single claim – no doctor visit, lab test, or prescription filled” in 2024.

The Paragon Health Institute study reports that this is triple the number of no-claim policyholders before the Biden sweeteners were put in place. “Among those now eligible for zero-premium plans with low or no deductible,” the study found, “that number increased nearly sevenfold. … A whopping 40 percent of enrollees in fully subsidized plans had no claims in 2024. In 2024 alone, taxpayers sent at least $35 billion to insurers for people who paid no premiums and never used their plan,” the report said.

Although many analysts suspect that these numbers suggest widespread fraud, Democrats and the insurance industry argue that they reflect consumers taking advantage of affordable coverage. They warn that the expiration of Biden-era reforms will make policies far more expensive for more than 20 million Americans. “If Congress fails to extend the health care tax credits, millions of Americans will face immediate and severe premium increases, leading many to forgo coverage altogether,” said Chris Bond, a spokesman for AHIP, the lobbying arm of the health insurance industry. “Congress must act as quickly as possible to protect Americans from this affordability crisis.”

As Democrats have made healthcare their line in the sand to avert a partial government shutdown on Oct. 1, Biden-era expansions of Obamacare are receiving new attention as a symbol of both expanding access to healthcare and of spending run amok.

Critics say they underscore the findings of the Department of Government Efficiency (DOGE), which has highlighted a lack of accountability in massive government spending programs at a time when the federal government is struggling to corral massive deficits and debt. They say the Biden sweeteners also illustrate how and why government spending keeps increasing: Once a subsidy is put in place, it is hard to take it away from voters.

Swollen Rolls

The Obamacare expansion at issue came about through legislation and regulations during Biden’s term and was often cast as a response to the COVID pandemic.

First, the scope of who was eligible for subsidies was broadened, making it available to households with incomes above 400% of the federal poverty line – making a family of four earning up to $160,000 eligible for subsidized plans. Also, increased subsidies made Obamacare free for those with incomes between 100% and 150% of the poverty line, and longer enrollment periods were created.

The cost for this, on the other hand, is borne by taxpayers.

“Biden’s COVID credits didn’t reduce health care costs – they just shifted them to taxpayers while padding insurer and enrollment intermediary profits,” Paragon President Brian Blase said.

Like all gigantic markets and massive government programs, the Affordable Care Act and what people pay each month have become a very complicated thing, varying by age, state, level of plan, and other factors. But the figures for the Obamacare “reference plan” (silver level) reveal what has happened since the COVID pandemic.

In 2021, when Biden was inaugurated, that basic plan cost an individual $27 a month if they reported income along the federal poverty line, which stood around $14,500 a year. For those making 50% more, the “reference plan” cost $75 a month, and so on up to $152 a month for someone making more than $30,000. Those monthly payment figures were constant regardless of what the insurers charged, with taxpayers making up the difference.

Through legislation Biden pushed through by narrow majorities or via reconciliation, the amount someone would pay each month in the first two categories dropped to zero. And as Obamacare became essentially free, millions signed up – enrolling at rates the plan had never seen since its inception in 2013. 

The overall figures reflect this explosion. Between 2016 and 2020, an average of 8.5 million people signed up for a subsidized Obamacare policy each year, and in none of those years did the figure equal 9 million, according to the Center for Medicare and Medicaid Services (CMS).

In 2021, however, the subsidized total topped 10 million, and by 2024 it had nearly doubled to 19.5 million, CMS figures show. 

“It’s all counter-intuitive, that when enrollment isn’t being publicized, no one is out beating the bushes to get people enrolled like we had in the early years of Obamacare,” said Ed Haislmaier, a healthcare expert at the conservative Heritage Foundation. “Amazing, that a product’s sales would go through the roof when nobody was talking about it.”

Some analysts believe the numbers indicate rampant fraud. Blase claimed in a letter to the Wall Street Journal that the expansion has created an explosion of phantom patients – including 6.4 million of them so far in 2025. “The problem isn’t real people with coverage they don’t use – it’s fraudulent sign-ups who never should have been subsidized.”

Haislmaier agreed, “We don’t have an exact number for how many people might be fake, I don’t think anyone does,” said Ed Haislmaier, “What we do have is a lot of circumstantial evidence, a lot of data points, and a lot of information about how the markets have always operated to suggest there is massive fraud here.”

Feds Smell a Rat

Paragon is not the only group voicing concerns. It often seems like fraud is endemic in federal programs, and government healthcare appears to offer a rich vein for such activity. 

In fact, CMS itself has warned of potentially rampant fraud and abuse sapping taxpayers through the revamped Obamacare exchanges. CMS focused on people unwittingly signed up for more than one plan, possibilities that multiplied when the Biden administration relaxed reviews of applicants and extended open enrollment periods.

CMS found in July that 2.8 million Americans were potentially enrolled “concurrently” in Medicaid and the Children’s Health Insurance Plan (CHIP) in more than one state, or on one of those federal programs plus the Obamacare exchange, resulting in inexplicable overlaps that could cost taxpayers $14 billion a year.

CMS insists its analysis is helping identify such problems, and that it is working with states and exchanges to strengthen eligibility verification processes and clean up enrollment data. The Trump administration has instituted some safeguards, such as sending state Medicaid agencies and state-based exchanges a list of individuals with possible concurrent enrollments so they can cross-check appropriate eligibility.

Opponents of expanded subsidies note that when the government makes a deep pool of money available, as has happened with the ACA, fraud is sure to follow. In June, Bloomberg did a deep dive on the phenomenon, describing a rat’s nest of unscrupulous call centers, primarily based in Florida, that have lured people in with various gimmicks and then signed them up for subsidized plans. 

What’s more, those licensed to sell plans had access to Obamacare exchange databases, which allowed them to change both the “agent of record” (thereby making themselves recipient of whatever bonus insurers paid for new signups), or the plan a person was enrolled in (thereby increasing their commission and the taxpayers’ bill), according to Gabrielle Kalisz, one of the authors of Paragon’s report.

Consequently, millions of Americans may be unaware that they own a subsidized Obamacare policy, and horror stories abound of unsuspecting people hit with tax bills seeking to recoup the subsidies.

“Nobody seems to have an incentive to be a good actor in the process,” Kalisz said. “The insurance companies are perfectly happy to keep getting the rising premiums, the navigators or agents are happy to keep getting the commissions, and Obamacare supporters are happy to act as if all this reflects people getting coverage.”

Nor are the so-called “phantom enrollees” the only issue. For example, the numbers don’t add up when percentages of state populations according to census data are measured against the Obamacare subsidies. Fourteen states have more people enrolled at up to 150% of the federal poverty line than they do residents who fit that category, and Florida’s total is five times what census data shows it could be.

“The enrollment fraud has become a massive problem,” said Michael Cannon, a healthcare expert at the libertarian Cato Institute. “The program has become like a great big ATM spitting out checks, and there’s very little policing going on because the government doesn’t care as much as it should about other people’s money.”

The new figures also diverge from what has been fairly consistent behavior in healthcare markets – another red flag, Haislmaier said. In 2019 and 2020, less than a quarter of policyholders never filed a claim. And the huge increase in so-called “phantom enrollees” doesn’t appear in market segments other than the now highly subsidized Obamacare plans. 

Such figures make no sense if they reflected genuine people aware of what coverage they were enrolled in, and bogus enrollment activity offers a clear explanation.

“This whole situation has been ideal for the fraudster,” he said. “Now you’ve got more enrolled than are eligible, subsidized plans spiking and non-subsidized plans flat. These are just all indicators that there is something whacky going on here.”

Subsidies or Shutdown?

All of this is informing the partisan debate over healthcare and efforts to fund the government after the current fiscal year ends on Sept. 30.

Republicans, including some who got fabulously wealthy through the healthcare system, like Florida’s Sen. Rick Scott, have said extending the subsidies is ruinously expensive and foolhardy, given what has happened since they were introduced. 

“COVID opened the door for massive waste, fraud, and abuse of government programs, like the billions in fraud and abuse allowed by the ‘temporary COVID’ enhanced Obamacare subsidies,” Scott posted last week. “Americans don’t want their tax dollars lining the pockets of insurance companies – it’s time to end this clear abuse of YOUR dollars.”

Scott drew attention to a Sept. 15 post by Wisconsin Republican Sen. Ron Johnson that made much the same point: “Extending the ‘temporary COVID’ enhanced Obamacare subsidies would perpetuate fraudulent activity, sending billions of dollars to insurance companies for policies that people are unaware they’re enrolled in and do not use,” he posted.

On the other side are Democrats who make strange political bedfellows of the insurance industry. Some who traditionally oppose big business, such as Massachusetts’ Sen. Elizabeth Warren or Vermont’s socialist Sen. Bernie Sanders, insist these recent subsidies must continue, preferably permanently. For them, the Obamacare rolls more than doubling – from 11.4 million to more than 24 million between 2020 and today – are a success sign of government-run healthcare.

Last week, Warren compared ending the subsidies to taking healthcare away from people.

“Still waiting to find out how Trump and Republicans think cutting health insurance for 15 million Americans makes America healthy again,” she posted on X Sept. 15. 

Polls suggest support for government-subsidized healthcare is a partisan issue. Last November, Gallup reported that “ninety percent of Democrats say that the federal government is responsible for American healthcare coverage, while 65% of Independents hold the same view. Although only 32% of Republicans share that opinion.” Another survey found that among those receiving subsidies, people who voted for Democrats outnumber Republicans by more than two to one.

Insurers say the Paragon study was flawed and accused the think tank of misunderstanding how insurance works. It’s not unusual for homeowners or car insurance policy holders to go years without filing a claim, and the same could be true with healthcare, they say. According to the industry and Democrats, the ballooning numbers reflect a thriving market in which many more Americans are enjoying healthcare coverage, as stated in a rebuttal released by AHIP on Aug. 15.

The debate will come to a head in the next week or so. President Trump this week rejected a meeting with congressional Democrats whose spending ideas he derided as fantastical. Republicans want to let the subsidies expire; Democrats want to make them permanent. 

Of course, that leaves some wiggle room, such as extending the subsidies for another year or some set period of time, a kicking-the-can option long favored by Congress. There have been some indications in the past several days that, public intransigence notwithstanding, negotiations might be ongoing.

Whatever the outcome, large subsidies that have always been part of Obamacare will continue. For all the hue and cry about rising costs, the elimination of Biden-era sweeteners would simply return the system to the way it was operating before 2021, Kalisz said.

“It’s crony math, a kind of corporate welfare,” she told RealClearInvestigations. “Why are the insurers now making it seem like all the subsidies are going away? It’s a form of scaring and spooking the public.”

_____________________________

The Leviticus 25 Plan will restore citizen-centered healthcare across America by paving forward a system in which millions of qualifying U.S. citizen families receive direct financial allocations to fund their own primary healthcare needs – and pay for insurance coverage that best fits their individual situations.

The Leviticus 25 Plan makes it possible for millions of Americans to pay directly for primary health care services, without government agency and insurance company involvement.

This will massively reduce the Medicaid rolls, massively reduce Medicare outlays, massively reduce the number of people who qualify for Obamacare ‘sweeteners.’

And it will eliminate layers of fraud woven into Medicaid, Medicare, Obamacare, and other entitlement programs like the Earned Income Tax Credit, Housing assistance, and others.

The Leviticus 25 Plan is the world’s most powerful economic rejuvenation plan in the world, It will generate $36.568 billion federal budget surpluses each of its first five years of activation (2026-2030) vs projected $2.1 trillion deficits.

And it will pay for itself entirely over the coming 10-15 years.

The Leviticus 25 Plan – An Economic Acceleration Plan for America

$95,000 per U.S. citizen – Leviticus 25 Plan 2026 (37132 downloads )