Record Low Consumer Sentiment: “Americans haven’t been this gloomy in 70 years.” – WSJ

WSJ: The Stock Market Has Never Been So Good When People Have Felt So Bad

Excerpt:

Americans are in a decidedly bad mood. The stock market is decidedly not.

This isn’t how it usually works. Instead, high stock prices have historically been associated with happy consumers, and vice versa. Here’s a look at what’s going on.

Just How Bad is Sentiment?

American attitudes just hit a milestone of sorts. On Friday, the University of Michigan reported that its index of consumer sentiment fell to the lowest level ever recorded in 70-odd years of surveys.

Sentiment was already low at the start of this year, but it fell sharply after the Iran war began at the end of February and sent gas prices sharply higher.

Until this year, the previous lowest level was in June 2022, when inflation was running at the highest level in decades. Friday’s sentiment reading was 10% below even that number. 

“Prices remain extremely high, labor markets have unambiguously weakened in the last four years, and now we’re in the middle of a war,” said Joanne Hsu, director of consumer surveys for the University of Michigan. “I don’t think the fact that we’re lower than June 2022 should come as a surprise to anyone.”

Full article: https://www.wsj.com/economy/consumers/stock-market-consumer-sentiment-af088e87

_________________________________

The vast majority of U.S. households fall beneath 90th percentile of the income and wealth distribution. This massive demographic, the “bottom 90%, captures a wide spectrum of Americans, from working-class individuals to middle-class professionals.

America’s record low consumer sentiment is primarily focused within this wide-ranging demographic, while at the same time, Wall Street has been feasting on record gains.

Democrat socialists in America are pushing hard for massive wealth redistribution, setting up ever greater levels of gloom and the eventual destruction of the U.S. economic system.

Main Street America Republicans have a plan that will eliminate massive amounts of debt, reignite economic growth and restore financial security for the millions of families counted among America’s “bottom 90%.”

This plan levels out the America’s economic playing field by granting hard-working, tax-paying U.S. citizens the same direct access to liquidity extensions that were so generously provided by the Federal Reserve (2008-2010 and 2021-2022) to the likes of: Morgan Stanley, Bank of America, Citigroup, JP Morgan, Goldman Sachs, State Street, AIG, Merrill Lynch, Wells Fargo… Barclays, UBS AG, Deutsche Bank, HSBC, Royal Bank of Scotland, BNP Paribas, Dexia, and numerous others.

The Leviticus 25 Plan – An Economic Acceleration Plan for America

$95,000 per U.S. citizen – Leviticus 25 Plan 2027 (53622 downloads )

Hubbard: “Bailouts Shouldn’t Be Only for Banks.”

Glenn Hubbard, dean of the Columbia Business School and former chairman of the Council of Economic Advisers during the George W. Bush presidency,. recently urged that financial crisis interventions should not be limited to banks.

………………………………………………

*Bailouts Shouldn’t Be Only for Banks – WSJ

Wall Street Journal, 9-14-18 – Excerpts:

“To be sure, recapitalizing financial institutions was an important element of the policy response. The depletion of capital buffers before the crisis reduced loan supply and exacerbated fire sales of distressed assets once the market collapsed. Cash infusions by the Treasury under the Troubled Asset Relief Program, in concert with the Fed’s bold lender-of-last-resort interventions, blunted the impact of the crisis.

That said, the perceived lack of attention to “Main Street” fed public suspicion of the bailouts. The government appeared to be more interested in addressing the decline in bank capital than the decline in home values. Millions of homeowners who were current in their mortgage payments were unable to refinance at lower interest rates because they were underwater. Yet many of these mortgages were already guaranteed by Fannie Mae and Freddie Mac , meaning taxpayers held the credit risk. Banks and investors holding the mortgages would never receive less than par.

The government should have directed a mass refinancing of mortgages for primary homes in which the borrower was current in payments. This would have led to an increase in disposable income and in home prices totaling more than $100 billion, according to a proposal Christopher Mayer and I offered at the time. The Treasury instead offered a tepid version of this with the Home Affordable Modification Program and the Home Affordable Refinance Program. These initiatives lacked the boldness of the bank bailouts, and Americans noticed…”

Hubbard concluded, “Ten years on, the U.S. still lacks a detailed plan for postcrisis intervention…”

____________________________

What America really needs, to restore financial health to working families and ‘power up’ economic vitality throughout Main Street America – is a detailed plan for ‘pre-crisis’ intervention.

America needs a comprehensive economic plan that will insulate Main Street America’s hard-working, tax-paying U.S. citizens from the next financial crisis, shrink government’s massive footprint in controlling the lives of free Americans, and generate massive new tax revenue flows with a powerful, sustainable reduction in government deficits.

America’s new economic plan is currently loaded up and ready to launch…

The Leviticus 25 Plan – An Economic Acceleration Plan for America

$95,000 per U.S. citizen – Leviticus 25 Plan 2027 (52432 downloads )

Reminder: List of Biden Tax Hikes that Kicked In Jan 1, 2023

A look back…

Here’s A List Of Biden Tax Hikes Which Take Effect Jan. 1

ZeroHedge, Dec 31, 2022 – Excerpts:

When the Democrats finally passed the “Inflation Reduction Act” in 2022 (how’s that going?), they included several tax hikes set to take effect on Jan. 1, 2023.

Americans for Tax reform‘s Mike Palicz has conveniently compiled a list of them, along with his take on their intended effects:

$6.5 Billion Natural Gas Tax Which Will Increase Household Energy Bills   

Think your household energy bills are high now? Just wait until the three major energy taxes in the Inflation Reduction Act hit your wallet. The first is a regressive tax on American oil and gas development. The tax will drive up the cost of household energy bills. The Congressional Budget Office estimates the natural gas tax will increase taxes by $6.5 billion.

And of course, this tax hike violates Biden’s pledge not to raise taxes on Americans making under $400,000 per year. According to the American Gas Association, the methane tax will slap a 17% increase on the average family’s natural gas bill.

$12 Billion Crude Oil Tax Which Will Increase Household Costs

Next up – a .16c/barrel tax on crude oil and imported petroleum products which will end up on the shoulders of consumers in the form of higher tax prices.

The tax hike violates President Biden’s tax pledge to any American making less than $400,000 per year.

As noted above, Biden administration officials have repeatedly admitted taxes that raise consumer energy prices are in violation of President Biden’s $400,000 tax pledge.

As if it weren’t bad enough, Democrats have pegged their oil tax increase to inflation. As inflation increases, so will the level of tax.

$1.2 Billion Coal Tax Which Will Increase Household Energy Bills

This one increases the current tax rate on coal from $0.50 to $1.10 per ton, while coal from surface mining would increase from $0.25 per to to $0.55 per ton, which will raise $1.2 billion per year in taxes that will undoubtedly be passed along to consumers in the form of higher energy bills.

$74 Billion Stock Tax Which Will Hit Your Nest Egg — 401(k)s, IRAs and Pension Plans

Democrats are now imposing a new federal excise tax when Americans sell shares of a stock back to a company.

Raising taxes and restricting stock buybacks harms the retirement savings of any individual with a 401(k), IRA or pension plan.

Union retirement plans will also be hit.

The tax will put U.S. employers at a competitive disadvantage with China, which does not have such a tax.

Stock buybacks help grow retirement accounts. Raising taxes and restricting buybacks would harm the 58 percent of Americans who own stock and more than 60 million workers invested in a 401(k). An additional 14.83 million Americans are invested in 529 education savings accounts.

Retirement accounts hold the largest share of corporate stocks, accounting for roughly 37 percent of the outstanding $22.8 trillion in U.S. corporate stock, according to the Tax Foundation.

In 2017, corporate-sponsored funds made up $4.45 trillion in market value; union-sponsored funds accounted for $409 billion; and public-sponsored funds, which benefit teachers and police officers, added up to $4.25 trillion.

A tax on buybacks could dissuade companies from doing so, and US companies will face significant compliance costs, which will – again, be passed along to consumers.

$225 Billion Corporate Income Tax Hike Which Will Be Passed on to Households

American businesses reporting at least $1 billion in profits over the past three years will now face a 15% corporate alternative minimum tax, which will be passed along in the form of higher prices, fewer jobs and lower wages, according to Americans for Tax Reform.

A Tax Foundation report from last December found a 15 percent book tax would reduce GDP by 0.1 percent and kill 27,000 jobs.

Preliminary cost estimates from the Congressional Budget Office found the provision would increase taxes by more than $225 billion.

According to JCT’s analysis, 49.7 percent of the tax would be borne by the manufacturing industry at a time when manufacturers are already struggling with supply-chain disruptions.

Which industry will likely be most affected? According to the Tax Foundation, “the coal industry faces the heaviest burden of the book minimum tax, facing a net tax hike of 7.2 percent of its pretax book income, followed by automobile and truck manufacturing, which faces a 5.1 percent tax hike.”

_________________________________ 

Main Street America Republicans have the one and only plan in America with the power to monumentally shrink the big government footprint that is strangling U.S. economic growth

The Leviticus 25 Plan is a dynamic economic initiative providing direct liquidity benefits for American families, while at the same time scaling back the role of government in managing and controlling the affairs of citizens.  It is a comprehensive plan with long-term economic and social benefits for citizens and government.

The inspiration for this plan is based upon Biblical principles set forth in the Book of Leviticus, principles tendering direct economic liberties to the people.

The Leviticus 25 Plan – An Economic Acceleration Plan for America

$95,000 per U.S. citizen – Leviticus 25 Plan 2027 (52031 downloads )

Property Tax Rebellion Now Boiling Over in America. One Dynamic Plan Provides Everything Needed to Solve This Crisis and Get America Back on Track…

The property tax relief plans named in the story below center around shifting tax burdens and squeezing already strained budgets, but do nothing to alleviate overall tax burdens for citizens and businesses.

They do nothing to reverse overall massive state and local budget deficits.

They do nothing to eliminate federal budget deficits – projected by the Congressional Budget Office (CB) to grow from $1.9 trillion in 2026 to $3.1 trillion by 2036 – and generate a powerful new flow of federal budget surpluses.

Finally, the strategies named below will do nothing to lift people up out of poverty, eliminate massive amounts of Household Debt, and restore financial security for millions of America’s hard-working, tax-paying U.S. citizens.

Meet the one plan in America that will resolve these critical issues: The Leviticus 25 Plan

………………………………………

A Property Tax Rebellion Is Emerging In America

ZeroHedge, May 04, 2026 – Authored by Aaron Gifford via The Epoch Times,

Excerpts:

…If 413,000 residents throughout the Buckeye State sign a petition before July 1, a public vote to eliminate local property taxes will appear on the November ballot.

If the signature count falls short, whatever is collected can be applied the following year, or however long it takes, said Blackmarr, media coordinator and a main volunteer for the 3,000-plus member Citizens for Property Tax Reform group.

“We are really hurting in Ohio,” she told The Epoch Times. “People never thought they’d be in this situation.”

Ohio isn’t alone. Forty-six states and the District of Columbia already have limits on annual local property tax levy increases, and leaders in Florida and Texas are pursuing additional legislation to limit government “flexibility” in how it raises revenues, according to a September report from McKinsey and Co., a global management consulting firm whose clients include state and local governments.

Schools, already strapped for cash, hang in the balance. School districts struggle with declining student enrollment, unfunded mandates, state and federal aid loss largely due to skyrocketing Medicaid costs, and spiking employee health insurance costs.

On the local level, mayors and town boards face similar challenges as they try to continue providing public safety, utilities, and infrastructure services.

Fed-up homeowners say it’s high time to try another way to pay their community’s civil servants, perhaps through higher sales tax or state income tax rates, along with slashing administrative bloat in schools and city halls.

“Let the state find a way where 100 percent of the population pays for education,” Ron Shumate, one of Blackmarr’s volunteers from suburban Cincinnati, told The Epoch Times. “They give profit-making businesses a break, but not us.”…

Across States and Communities

In Massachusetts, a citizens group in Great Barrington, near Springfield, wants to shift more of the costs for schools and local infrastructure to part-time residents who own vacation homes. If All Band Together gets its way, the current annual property tax on a full-time residence assessed at $200,000, for example, would decrease by $1,293, while the amount for a seasonal home with the same assessment would increase by $356, according to the group’s website.

In Minnesota and North Dakota, Republican lawmakers have proposed a cap on property tax increases based on the rate of inflation and population growth. If the rate of inflation is 3 percent and the population of a community grows by 1 percent, for example, then the increase cap for the taxing entity would be 3.5 percent. Overriding the cap would require voter approval.

John Phelan, an economist for Minnesota-based Center of the American Experiment, which wrote the model legislation for both states, said the proposal was prompted by property tax hikes last year of between 8 percent and 9.5 percent in some counties. School boards decide on annual district operating budgets and subsequent tax levies; voters only have a say on major expenditures beyond personnel and fixed costs, such as the creation of a multimillion-dollar technology fund.

“The burden shouldn’t be driven by asset values,” Phelan told The Epoch Times. “If [school districts] want to spend more money, they should get permission from the population.”

In Montana, Republican state lawmakers are pursuing a 2 percent cap on property tax hikes for local government funding, but not for schools, which consume about 55 percent of property tax revenues.

Kendall Cotton, president and CEO of the Frontier Institute research and policy center, called the legislation a good start, but said more relief is needed, as home appraisals in growing communities increased by 60 percent this year, resulting in double-digit property tax hikes….

“These big jumps put a lot of pressure on the system, but governments have not been responding in kind,” Cotton told The Epoch Times.

“Misplaced priorities,” he said. “People are really being taxed out of their homes. We are just renting from the government.”

Members of Nebraska’s Epic Option citizen group, like their peers in Ohio, are collecting signatures for a ballot initiative to eliminate property taxes. They paused their efforts to obtain the required 160,000 signatures this year and instead will focus on 2028, according to the group’s website….

Texas Gov. Greg Abbott suggested eliminating school property taxes, and Florida state lawmakers have proposed ending local government property taxes but not school taxes.

A bill in the Georgia state legislature calls for phasing out property taxes and increasing the sales tax. A similar bill was introduced in Pennsylvania. Various property tax reform measures have been proposed in Idaho, Illinois, Indiana, Iowa, Kansas, Oklahoma, South Dakota, and Wyoming, according to their respective state legislature websites.

School Budget Woes

More than one-third of U.S. public school funding comes from local property taxes, while the remainder is provided by state and federal aid, as well as municipal and state sales taxes, according to the National Center for Education Statistics. Some states also apply lottery and gambling revenues.

All told, K–12 spending across the country now exceeds $1 trillion, the Edunomics Lab at Georgetown University reported on April 23.

It also said public per-student spending ranges from about $11,000 in Idaho to more than $31,887 in the District of Columbia. Staffing and school tax rates continue to increase in most districts, while student enrollment decreases.

Typical state and federal aid formulas are based on enrollment, so districts must either cut costs or raise local taxes to offset the decreasing amount of per-student aid. The dependence on $189 billion in federal COVID-19 pandemic relief money, which prompted massive hiring sprees but is now exhausted, has exacerbated the financial crisis in many districts that serve low-income communities with large populations of special needs students…

Nationally, public K–12 enrollment decreased by about 900,500 students in the past decade, while staffing during the same time period increased by about 700,000, or 11.9 percent, according to the Edunomics Lab. The organization also reported planned school layoffs or staff reductions this year in Boston; Cleveland; Milwaukee; Las Vegas; Los Angeles; San Diego; San Francisco; Fresno, California; Richmond, Virginia; Tulsa, Oklahoma; Toledo, Ohio; Anchorage, Alaska; Cedar Rapids, Iowa;  Fort Lauderdale, Florida;  and “countless small and mid-sized districts.”

“This isn’t temporary,” the Edunomics Lab said in an email to The Epoch Times. “It’s a reset.”….

“The American dream is to own a home, work for at least 30 years, pay it off, retire 10 years later, and be comfortable,” … “If you’re relying on Social Security, that won’t happen.”

“People are tired of being taxed to death and seeing the money stolen,” …

Full article: https://www.zerohedge.com/personal-finance/property-tax-rebellion-emerging-america

____________________________________

The Leviticus 25 Plan will generate massive new tax revenue flows and reduce budget outlays on a broad scale – for federal, state, and local government agencies.

It does not ‘shift’ tax burdens. It eliminates tax burdens.

The Leviticus 25 Plan will give rise to the type of robust fiscal environment for state and local governments that will allow for property tax reductions beyond anything dreamed of in current, ongoing tax reduction discussions.

Teachers, faculty, administrators, support staff in America’s K-12 public and private schools and America’s higher education institutions who choose to participate will benefit enormously by the direct liquidity benefits of The Plan.

The Leviticus 25 Plan will generate $37.303 billion budget surpluses during each of its first five years of activation (2027-2031) – conservative economic scoring analysis – and pay for itself entirely over the succeeding 10-15 year period.

Finally, it will lift people up out of poverty, eliminate massive amounts of Household Debt, and restore financial security for millions of America’s hard-working, tax-paying U.S. citizens.

The Leviticus 25 Plan is a dynamic economic initiative providing direct liquidity benefits for American families, while at the same time scaling back the role of government in managing and controlling the affairs of citizens.  It is a comprehensive plan with long-term economic and social benefits for citizens and government.

The inspiration for this plan is based upon Biblical principles set forth in the Book of Leviticus, principles tendering direct economic liberties to the people.

The Leviticus 25 Plan – An Economic Acceleration Plan for America

$95,000 per U.S. citizen – Leviticus 25 Plan 2027 (51641 downloads )
The Leviticus 25 Plan – Economic Dynamics for Main Street America (2027-2031)

Overview – “Consumer expenditures on interest payments represent a significant portion of household budgets, exceeding $1.1 trillion last quarter. These payments, covering non-mortgage debt like credit cards and auto loans, have risen significantly due to higher interest rates aimed at combating inflation, according to data from the U.S. Bureau of Economic Analysis (BEA).”

………………………………………….

US Mortgage Statistics 2026: Debt, Delinquency and Foreclosure Data

Written by  Maggie Davis |  Edited by  Dan Shepard  |  Updated Mar 25, 2026

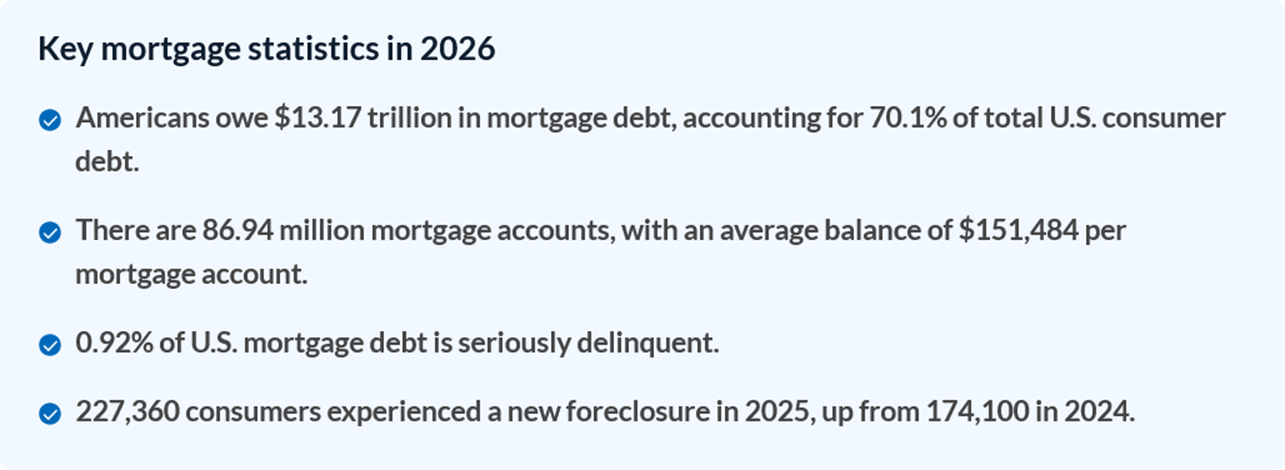
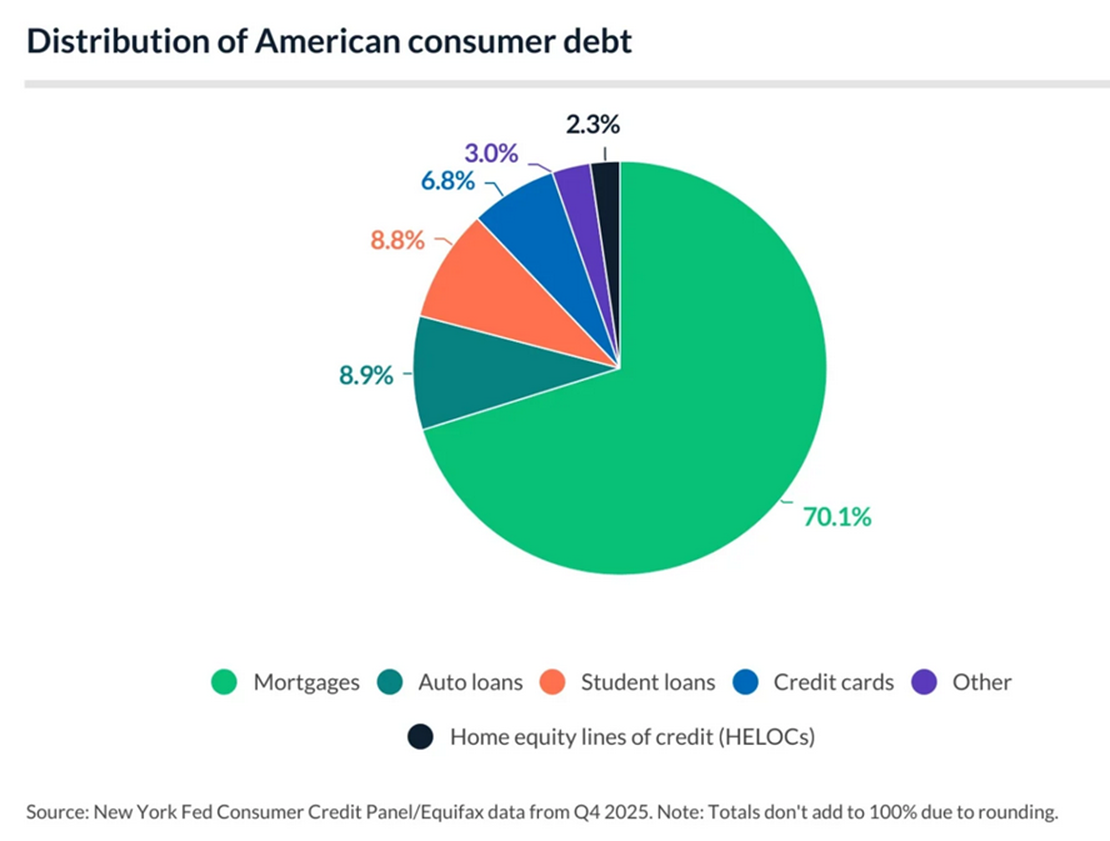
Americans collectively owe $13.17 trillion in mortgage debt, accounting for 70.1% of total U.S. consumer debt. Just 0.92% of mortgage debt is seriously delinquent, indicating that most borrowers are keeping up with their payments.

…………………………………………..

Household Debt and Credit Developments in 2025Q41

Federal Reserve Bank of New York – Quarterly Report on Household Debt and Credit 2025:Q4

Total Household Debt now stands at $18.8 trillion.

Non-mortgage household debt rose $191 billion in 2025Q4 to $5.164 trillion.

Mortgage Balances
• Mortgage balances grew by $98 billion during Q4 2025, totaling $13.17 trillion at the end of December;
• Home equity lines of credit “outstanding HELOC balances,” up $12 billion, to $433 billion.

Non-housing Consumer Debt
• Non-housing consumer debt balances increased by $81 billion to $5.164 trillion;
• Credit card balances rose $44 billion during the fourth quarter, now totaling $1.28 trillion;
• Auto loan balances edged up by $12 billion to $1.66 trillion;
• Other balances, which include retail cards and consumer finance loans, rose $14 billion to $564 billion;
• Student loan balances increased $11 billion in the quarter – current total $1.66 trillion.

Delinquency & Public Records
Aggregate delinquency rates worsened slightly in the fourth quarter of 2025. As of the end of December, 4.8% of outstanding debt was in some stage of delinquency… Transition into early delinquency ticked up slightly for mortgages and more significantly for student loans, but held mostly steady for autos, credit cards, and HELOCs.

___________________________________

The Leviticus 25 Plan will, at a minimum, eliminate several trillion dollars in consumer non-mortgage debt and satisfy delinquent debt obligations and clear bankruptcy notices for over 200,000 consumers.

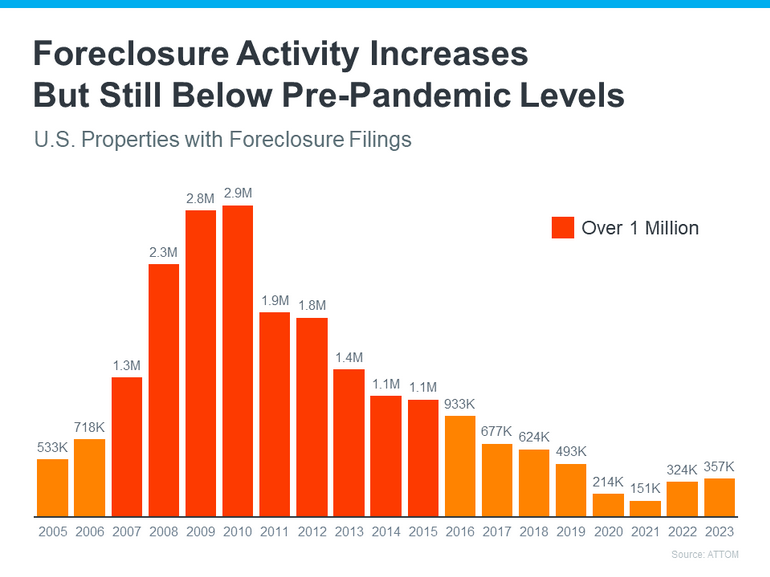
The Leviticus 25 Plan will also draw down / eliminate trillions of dollars in Home Mortgages and Home Equity Lines of Credit (HELOC), and clear the majority of loan delinquencies and foreclosure filings.

Shifting trillions of dollars from monthly debt service obligations into savings/investments and non-debt based economic growth will: 1) Generate massive new tax revenue flows and payroll tax gains for federal and state government; 2) Reinvigorate/rescue millions of struggling small businesses across America; 3) Restore financial security for millions of hard-working, tax-paying U.S. citizen families; 4) Provide the banking system with trillions of dollars in fresh cash reserves – with the potential of providing critical support for the U.S. Treasury market.

These economic dynamics add to The Leviticus 25 Plan‘s compelling fiscal dynamics, which on their own set the United States federal government on course for $37.303 billion budget surpluses during each of the first five years of activation (2027-2031), while vastly improving balance sheets of virtually all state/local government entities.

The Leviticus 25 Plan – the most powerful economic reset plan in the world. Loaded up and ready to launch.

The Leviticus 25 Plan – An Economic Acceleration Plan for America

$95,000 per U.S. citizen – Leviticus 25 Plan 2027 (50979 downloads )

Paulson Treasury Market Warning: “We need an emergency break-the-glass plan”

Is A “Vicious” Treasury Market Emergency At Our Doorstep?

ZeroHedge, Apr 19, 2026 –  Submitted by QTR’s Fringe Finance

Excerpts:

…When Henry Paulson steps back into the public conversation after years of relative silence, it’s not random timing. This is someone who sat at the center of the 2008 financial crisis and understands how quickly confidence can evaporate once stress begins to build in core markets….Paulson is explicitly warning that the scale of U.S. borrowing is now testing confidence in the Treasury market itself. With federal debt approaching $39 trillion, he points to the risk that the long-standing assumption of endless demand for U.S. government debt may no longer hold.

As he put it, “That’s a dangerous thing,” describing a scenario where foreign demand declines and Treasury prices fall. That is not a small shift in tone. The entire global financial system is built on the idea that Treasuries are the ultimate safe asset, and once that perception begins to weaken, the consequences cascade quickly.

What stands out even more is what he says next about how such a situation would resolve: “Should enough investors back out… the Federal Reserve would step in as a buyer of last resort.”

And as we all know, a “buyer of last resort” is simply another way of describing a return to large-scale intervention by the Federal Reserve. Whether policymakers call it stabilization, liquidity support, or something else (like the A.S.S.H.O.L.E.S. plan), the mechanism is the same: the central bank absorbs supply when the market no longer can. In other words, quantitative easing returns.

That leaves two realistic interpretations of why Paulson is speaking now.

  1. Either he sees early signs of stress already forming beneath the surface of the Treasury market—declining foreign participation, weakening liquidity, or rising yields that are no longer being absorbed smoothly.
  2. Or he is helping prepare the narrative for the policy response that will follow when those stresses become undeniable. Those two possibilities are not mutually exclusive. In fact, they often occur together.

His comments about needing an emergency response framework make that even clearer. He said, “We need an emergency break-the-glass plan… ready to go when we hit the wall,” and followed it with “It will be vicious.”

Notice he said when we hit the wall, not if.

That is not the language of a former official casually discussing long-term fiscal challenges. It is the language of someone who expects a disorderly adjustment and understands how quickly conditions can spiral once confidence breaks.

Markets already assume that after the next deleveraging cycle, central banks will return to QE. That part is widely understood. What is not fully appreciated is the implication if the stress originates inside the Treasury market itself. Treasuries are not just another asset class. They underpin global collateral systems, anchor borrowing costs across the economy, and support the U.S. dollar reserve currency status. If confidence in that market begins to erode, the feedback loop is far more severe than a typical recessionary downturn.

In that scenario, the Federal Reserve stepping in as the marginal buyer would not simply stabilize markets. It would fundamentally alter how capital allocates globally. Real yields could compress rapidly, confidence in fiat stability could weaken, and capital could rotate into hard assets at a pace that exceeds even aggressive expectations. The move would not just be cyclical, it would be structural.

The second-order risk is even more significant. If foreign demand for Treasuries fades and the U.S. increasingly relies on its own central bank to finance deficits, the signal to the rest of the world is unmistakable. That is how pressure begins to build on a reserve currency. An FX adjustment tied to the dollar is not the base case today, but neither was a systemic breakdown in mortgage markets prior to 2008. These transitions always look implausible until they are suddenly obvious.

The key point is that Paulson is not someone who reappears without purpose. He understands the plumbing of the system and the fragility that sits beneath it when leverage is high and confidence is stretched. His warning that “We have to prepare for that eventuality” should not be dismissed as generic caution. It suggests that the risks are no longer theoretical.

There is more in his comments than a simple observation about rising debt levels. Either he sees stress forming already, or he is preparing markets for the policy response that will follow when that stress becomes visible. In both cases, the implication is the same: something larger is developing beneath the surface of the Treasury market, and when it breaks into the open, the consequences will extend far beyond bonds.

_____________________________

The Leviticus 25 Plan is a preemptive “emergency break-the-glass plan,” ready to go now — before we “hit the wall.”

The Leviticus 25 Plan re-targets Fed liquidity flows in a way that will preemptively generate substantial ongoing federal budget surpluses, structurally downsize federal, state, and local government outlays, eliminate massive amounts of household debt, and revitalize ‘non-debt-driven’ economic growth.

The most powerful decentralizing economic acceleration plan in the world.

The Leviticus 25 Plan – An Economic Acceleration Plan for America

$95,000 per U.S. citizen – Leviticus 25 Plan 2027 (50728 downloads )

Dijsselbloem (2017): “We used taxpayer money to bail out the banks.”

Jeroen Dijsselbloem – a major player in European financial circles.  A Dutch politician, Dijsselbloem became President of the Eurogroup, comprised of the finance ministers of the Eurozone, in January 2013 and served in that capacity until just recently. He offered a frank admission just last month about the naked, taxpayer-financed bailout of major banks.

…………………………………………..

A look back…

Dijsselbloem Admits “We Used Taxpayers’ Money To Bailout The Banks”

ZeroHedge, Nov 10, 2017:  Excerpts:

“We had a banking crisis, a fiscal crisis and we spent lot of the tax-payers’ money – in the wrong way, in my opinion – to save the banks” outgoing Eurogroup head Jeroen Dijsselbloem said adding “so that the people criticizing us and saying that everything was being done for the benefit of the banks were to some extent right.”

“This is valid for the banks of all our countries. Everywhere in Europe banks were saved at taxpayers’ cost,” he underlined.

“This was the reason for banking union and the introduction of higher standards, better supervision and a reform and rescue framework when banks have losses,” he said stressing  “precisely so that we don’t find ourselves in that situation again.”

__________________________

Again…:  “This is valid for the banks of all our countries. Everywhere in Europe banks were saved at taxpayers’ cost.”

Exactly the same in the U.S. – The Fed did what it had to do to prevent a credit crisis meltdown.

Now it is time to level the playing field by granting U.S. citizens the same direct access to liquidity that was provided to Wall Street’s financial sector.

Taxpayers bailed out the very institutions which precipitated a financial crisis which hit Main Street America long and hard, and in many ways, lingers on. The time is now at hand for The Leviticus 25 Plan Citizens Credit Facility activation – to restore the financial health and well being of Main Street America and U.S. taxpayers.

The Leviticus 25 Plan – An Economic Acceleration Plan for America

$95,000 per U.S. citizen – Leviticus 25 Plan 2027 (50383 downloads )

Nov 2008: Deutsche Bank AG received $66 billion in ‘secret liquidity’ funding from Fed. In retrospect – a total waste.

A look back…

Deutsche Bank, AG, along with numerous foreign banking interests with U.S. subsidiaries, enjoyed massive liquidity infusions, courtesy of the U.S. Federal Reserve, to help them deal with their faltering financial conditions and mounting debt burdens during the great financial crisis 2007-2010.

Excerpts from:  Bloomberg  Nov 28, 2011:    

“Deutsche Bank AG, Germany’s biggest bank, navigated the financial crisis without capital injections from the German government. The Frankfurt-based bank, which in 2008 reported its first annual loss since World War II, wasn’t so shy about getting liquidity in secret from the U.S. Federal Reserve. The lender tapped the Fed for $66 billion on Nov. 6, 2008 — $28.2 billion from the Term Securities Lending Facility, $21.8 billion from single-tranche open market operations and $16 billion from the Term Auction Facility. John Gallagher, a Deutsche Bank spokesman, declined to say whether the bank took emergency loans during the crisis from other central banks, such as Germany’s Bundesbank.”

Peak amount of debt held on 11-6-2008:  $66B  

……………………………………………………………………….

During the two years leading into Deutsche Bank’s financial windfall from the U.S. Fed, it was also engaged in the “Sale of toxic securities leading up to the financial crisis” and a Libor Interest Rate Scam” which defrauded U.S. tax-paying citizens via excessive interest charges on municipal loans. Source: Deutsche Bank’s Five Biggest Scandals

“Deutsche Bank was one of a series of lenders guilty of selling and pooling toxic financial products in the lead-up to the 2007 and 2008 financial crisis.”

“The bank signed a $7.2 billion settlement with the US Department of Justice in 2017, after being accused of having sold investors bad mortgage-backed securities between 2005 and 2007…”

Deutsche Bank’s charges involved “espionage, money laundering and interest rate scams,” including:

1. Laundering Russian money – In 2017, Deutsche Bank was fined a total of $630 million (€553.5 million) by US and UK financial authorities over accusations of having laundered money out of Russia.

2. Libor interest rate scam – Deutsche Bank had already been fined a record $2.5 billion dollars bv US and British authorities for its role in an interest scam between 2003 and 2007.

The bank’s London subsidiary pleaded guilty to counts of criminal wire fraud, after it was accused of fixing interest rates like the London Interbank Offered Rate (Libor), used to price a hefty amount of loans and contracts across the world. 

3. “Violating U.S. economic sanctions” involving countries like Iran, Libya, Sudan

___________________________________________

Meanwhile, during the great financial crisis, a Bureau of Labor statistics report showed that between 2008 and 2010, the U.S. economy suffered the worst employment crisis since the Great Depression, losing roughly 8.4 to 8.6 million jobs. Job losses accelerated rapidly in late 2008, peaking with an average of 700,000+ monthly losses from October 2008 to March 2009. Unemployment peaked at 10% in October 2009, with employment not hitting its lowest point until February 2010.

Subprime mortgage lending exploded during 2004-2006, creating the infamous housing market bubble, precipitating the housing market crash, followed by millions of Americans losing their jobs during the fallout… and then losing their homes as millions of foreclosures swamped the housing market.

If the U.S. Federal Reserve can transfuse the likes of Deutsche Bank with $66 billion in ‘secret liquidity funding’…

Then U.S. citizens deserve nothing less than to be granted that same direct access to liquidity – to deal with their own “mounting debt burdens.”

The Leviticus 25 Plan generates $37.303 billion federal budget surpluses annually during its first five years of activation (2027-2031) – and pays for itself entirely over the succeeding 10-15 year period.

The Leviticus 25 Plan is a dynamic economic initiative providing direct liquidity benefits for American families, while at the same time scaling back the role of government in managing and controlling the affairs of citizens.  It is a comprehensive plan with long-term economic and social benefits for citizens and government.

The inspiration for this plan is based upon Biblical principles set forth in the Book of Leviticus, principles tendering direct economic liberties to the people.

The Leviticus 25 Plan – An Economic Acceleration Plan for America

$95,000 per U.S. citizen – Leviticus 25 Plan 2027 (50315 downloads )

Andrew Huszar, Federal Reserve Official: QE was “the greatest backdoor Wall Street bailout of all time”

A look back…

………………………………..

Andrew Huszar: Confessions of a Quantitative Easer – WSJ

Nov 11, 2013: Andrew Huszar directed the Federal Reserve’s [QE1] $1.25 trillion agency mortgage-backed security purchase program which kicked off during March 2009.

Here are his after-thoughts…or “confessions”  (Andrew Huszar: “Confessions of a Quantitative Easer”) excerpts: 

“We went on a bond-buying spree that was supposed to help Main Street. Instead, it was a feast for Wall Street. 

I can only say: I’m sorry, America. As a former Federal Reserve official, I was responsible for executing the centerpiece program of the Fed’s first plunge into the bond-buying experiment known as quantitative easing. The central bank continues to spin QE as a tool for helping Main Street. But I’ve come to recognize the program for what it really is: the greatest backdoor Wall Street bailout of all time. 

Five years ago this month, on Black Friday, the Fed launched an unprecedented shopping spree. By that point in the financial crisis, Congress had already passed legislation, the Troubled Asset Relief Program, to halt the U.S. banking system’s free fall. Beyond Wall Street, though, the economic pain was still soaring. In the last three months of 2008 alone, almost two million Americans would lose their jobs.

The Fed said it wanted to help—through a new program of massive bond purchases. There were secondary goals, but Chairman Ben Bernanke made clear that the Fed’s central motivation was to “affect credit conditions for households and businesses”: to drive down the cost of credit so that more Americans hurting from the tanking economy could use it to weather the downturn. For this reason, he originally called the initiative “credit easing.”

In its almost 100-year history, the Fed had never bought one mortgage bond. Now my program was buying so many each day through active, unscripted trading that we constantly risked driving bond prices too high and crashing global confidence in key financial markets. We were working feverishly to preserve the impression that the Fed knew what it was doing. 

It wasn’t long before my old doubts resurfaced. Despite the Fed’s rhetoric, my program wasn’t helping to make credit any more accessible for the average American. The banks were only issuing fewer and fewer loans. More insidiously, whatever credit they were extending wasn’t getting much cheaper. QE may have been driving down the wholesale cost for banks to make loans, but Wall Street was pocketing most of the extra cash.

Trading for the first round of QE ended on March 31, 2010. The final results confirmed that, while there had been only trivial relief for Main Street, the U.S. central bank’s bond purchases had been an absolute coup for Wall Street. The banks hadn’t just benefited from the lower cost of making loans. They’d also enjoyed huge capital gains on the rising values of their securities holdings and fat commissions from brokering most of the Fed’s QE transactions. Wall Street had experienced its most profitable year ever in 2009, and 2010 was starting off in much the same way.

That was when I realized the Fed had lost any remaining ability to think independently from Wall Street. Demoralized, I returned to the private sector.

Where are we today [2013]? The Fed keeps buying roughly $85 billion in bonds a month, chronically delaying so much as a minor QE taper. Over five years, its bond purchases have come to more than $4 trillion. Amazingly, in a supposedly free-market nation, QE has become the largest financial-markets intervention by any government in world history. 

And the impact? Even by the Fed’s sunniest calculations, aggressive QE over five years has generated only a few percentage points of U.S. growth. By contrast, experts outside the Fed, such as Mohammed El Erian at the Pimco investment firm, suggest that the Fed may have created and spent over $4 trillion for a total return of as little as 0.25% of GDP (i.e., a mere $40 billion bump in U.S. economic output). Both of those estimates indicate that QE isn’t really working.

Having racked up hundreds of billions of dollars in opaque Fed subsidies, U.S. banks have seen their collective stock price triple since March 2009. The biggest ones have only become more of a cartel: 0.2% of them now control more than 70% of the U.S. bank assets.”

_____________________________

Again…

Andrew Huszar – Federal Reserve QE1: “The final results confirmed that, while there had been only trivial relief for Main Street, the U.S. central bank’s bond purchases had been an absolute coup for Wall Street. The banks hadn’t just benefited from the lower cost of making loans. They’d also enjoyed huge capital gains on the rising values of their securities holdings and fat commissions from brokering most of the Fed’s QE transactions.”

The Leviticus 25 Plan redresses Wall Street’s “absolute coup” from the Fed’s 2008-2010 QE1 bond purchases by granting direct liquidity extensions to qualifying U.S. citizens, to achieve massive debt elimination and restored financial health for millions of hard-working, tax-paying families

The Leviticus 25 plan will generate dynamic growth in the U.S. economy and prosperity for the 36.2 million small businesses spread out across Main Street America. 

The Leviticus 25 Plan is a dynamic economic initiative providing direct liquidity benefits for American families, while at the same time scaling back the role of government in managing and controlling the affairs of citizens.  It is a comprehensive plan with long-term economic and social benefits for citizens and government.

The inspiration for this plan is based upon Biblical principles set forth in the Book of Leviticus, principles tendering direct economic liberties to the people.

The Leviticus 25 Plan – An Economic Acceleration Plan for America

$95,000 per U.S. citizen – Leviticus 25 Plan 2027 (50096 downloads )

Enhanced Supplementary Leverage Ratio for GSIBs – and The Leviticus 25 Plan

Federal bank regulatory agencies have finalized a rule to modify the Enhanced Supplementary Leverage Ratio (eSLR) standards, effective April 1, 2026 (with optional early adoption on January 1, 2026). The final rule lowers capital requirements for large U.S. banks (GSIBs), reducing the fixed 2% eSLR buffer to a variable amount equal to 50% of a bank’s Method 1 GSIB surcharge, which frees up balance sheet capacity and acts as a complement to strategies aimed at increasing bank participation in low-risk activities, such as Treasury market intermediation.

…………………….

AI Overview
Key Details of the Final Rule:

  • Effective Date: April 1, 2026, with an option for early adoption on January 1, 2026.
  • Targeted Entities: U.S. Global Systemically Important Bank holding companies (GSIBs) and their subsidiary depository institutions.
  • Buffer Reduction: The eSLR buffer for covered depository institutions is capped at 1% above the minimum 3% leverage ratio, rather than the previous 2% buffer, according to Federal Register (.gov) and Office of the Comptroller of the Currency (OCC) (.gov).
  • Purpose: To reduce the punitive capital charges on low-risk activities, such as U.S. Treasury market intermediation, and adjust capital standards based on systemic risk, according to Federal Reserve Board (.gov) and JD Supra.
  • Impact: The changes are expected to lower funding costs and reduce Tier 1 capital requirements for holding companies by an estimated $13 billion, according to Federal Deposit Insurance Corporation (FDIC) (.gov) and JD Supra. 

Source: Regulatory Capital Rule: Modifications to the Enhanced Supplementary Leverage Ratio Standards for U.S. Global Systemically Important Bank Holding Companies and Their Subsidiary Depository Institutions; Total Loss-Absorbing Capacity and Long-Term Debt Requirements for U.S. Global Systemically Important Bank Holding Companies

A Rule by the Comptroller of the Currency, the Federal Reserve System, and the Federal Deposit Insurance Corporation on 12/01/2025

_____________________________   …

The Leviticus 25 Plan would be a perfect complement to this new regulatory change in the Enhanced Supplemental Leverage Ratio (eSLR) for banks.

This regulatory change alone will be “bullish catalyst for treasuries” … allowing “banks to hold more Treasuries on their balance sheets without needing to hold additional capital against them, freeing up the capacity for banks to participate more actively in the Treasury market.” (The Bear Traps Report, Dec 20, 2024)

The Leviticus 25 Plan, through the satisfaction of private sector debt (mortgage debt, student loan debt, household debt, auto loans, credit card debt), would provide a powerful additional enhancement of the eSLR change, with trillions of new dollars flowing into the banking system.  This synergism would allow GSIBs (global systemically important bank holding companies) even greater treasury auction purchasing power, with increased competitive bidding, lower interest rates, and long-term strength and stability for the U.S. Dollar.

The Leviticus 25 Plan would allow the Fed to adjust interest rates in response to price discovery and free market dynamics, rather than reacting to complex statistical evaluations and timing models, not to mention often intense political pressures.

Occasional adjustments over the course of time toward higher rates, to cool sporadic excesses and speculation within the economy, would decrease the likelihood of new ‘bubbles’ popping up in financial markets.  It would be much better tolerated in this new low-debt environment, and it would allow savers to earn millions of dollars in additional interest on their savings.

The Leviticus 25 Plan’s massive public and private debt elimination dynamic will immediately:
1) Generate $37.303 billion federal budget surpluses annually during its first five years of activation (2027-2031), it will pay for itself entirely over the succeeding 10-15 year period, and contribute highly favorable budget gains for state and local government entities;
2) Lower short-term and long-term interest rates;
3) Reduce fraud and waste across many of government’s social insurance sectors;
4) Restore real financial security for millions of American families, rekindle the spirit of self-reliance, and scale back out-of-control government entitlement spending;
5) And generate a long-term economic growth cycle that would benefit all Americans, most notably the 33.2 million small businesses across the U.S..2) Lower short-term and long-term interest rates;

The Leviticus 25 Plan – the most powerful decentralizing economic acceleration plan in the world – is loaded up and ready to launch.

The Leviticus 25 Plan is a dynamic economic initiative providing direct liquidity benefits for American families, while at the same time scaling back the role of government in managing and controlling the affairs of citizens.  It is a comprehensive plan with long-term economic and social benefits for citizens and government.

The inspiration for this plan is based upon Biblical principles set forth in the Book of Leviticus, principles tendering direct economic liberties to the people.

The Leviticus 25 Plan – An Economic Acceleration Plan for America

$95,000 per U.S. citizen – Leviticus 25 Plan 2027 (48914 downloads )